
Table of Contents
Never Boring AI — Investment Report
Product Hunt: Never Boring AI
Spreadsheet launch date: October 2, 2026
Assessment date: October 8, 2026
| Investment Metric | Assessment |
|---|---|
| Venture Potential | 62/100 |
| Unicorn Path | Conditional |
| Valuation Attractiveness | Not Assessable |
| Evidence Confidence | 62/100 |
| Final Decision | Watch |
Executive Summary
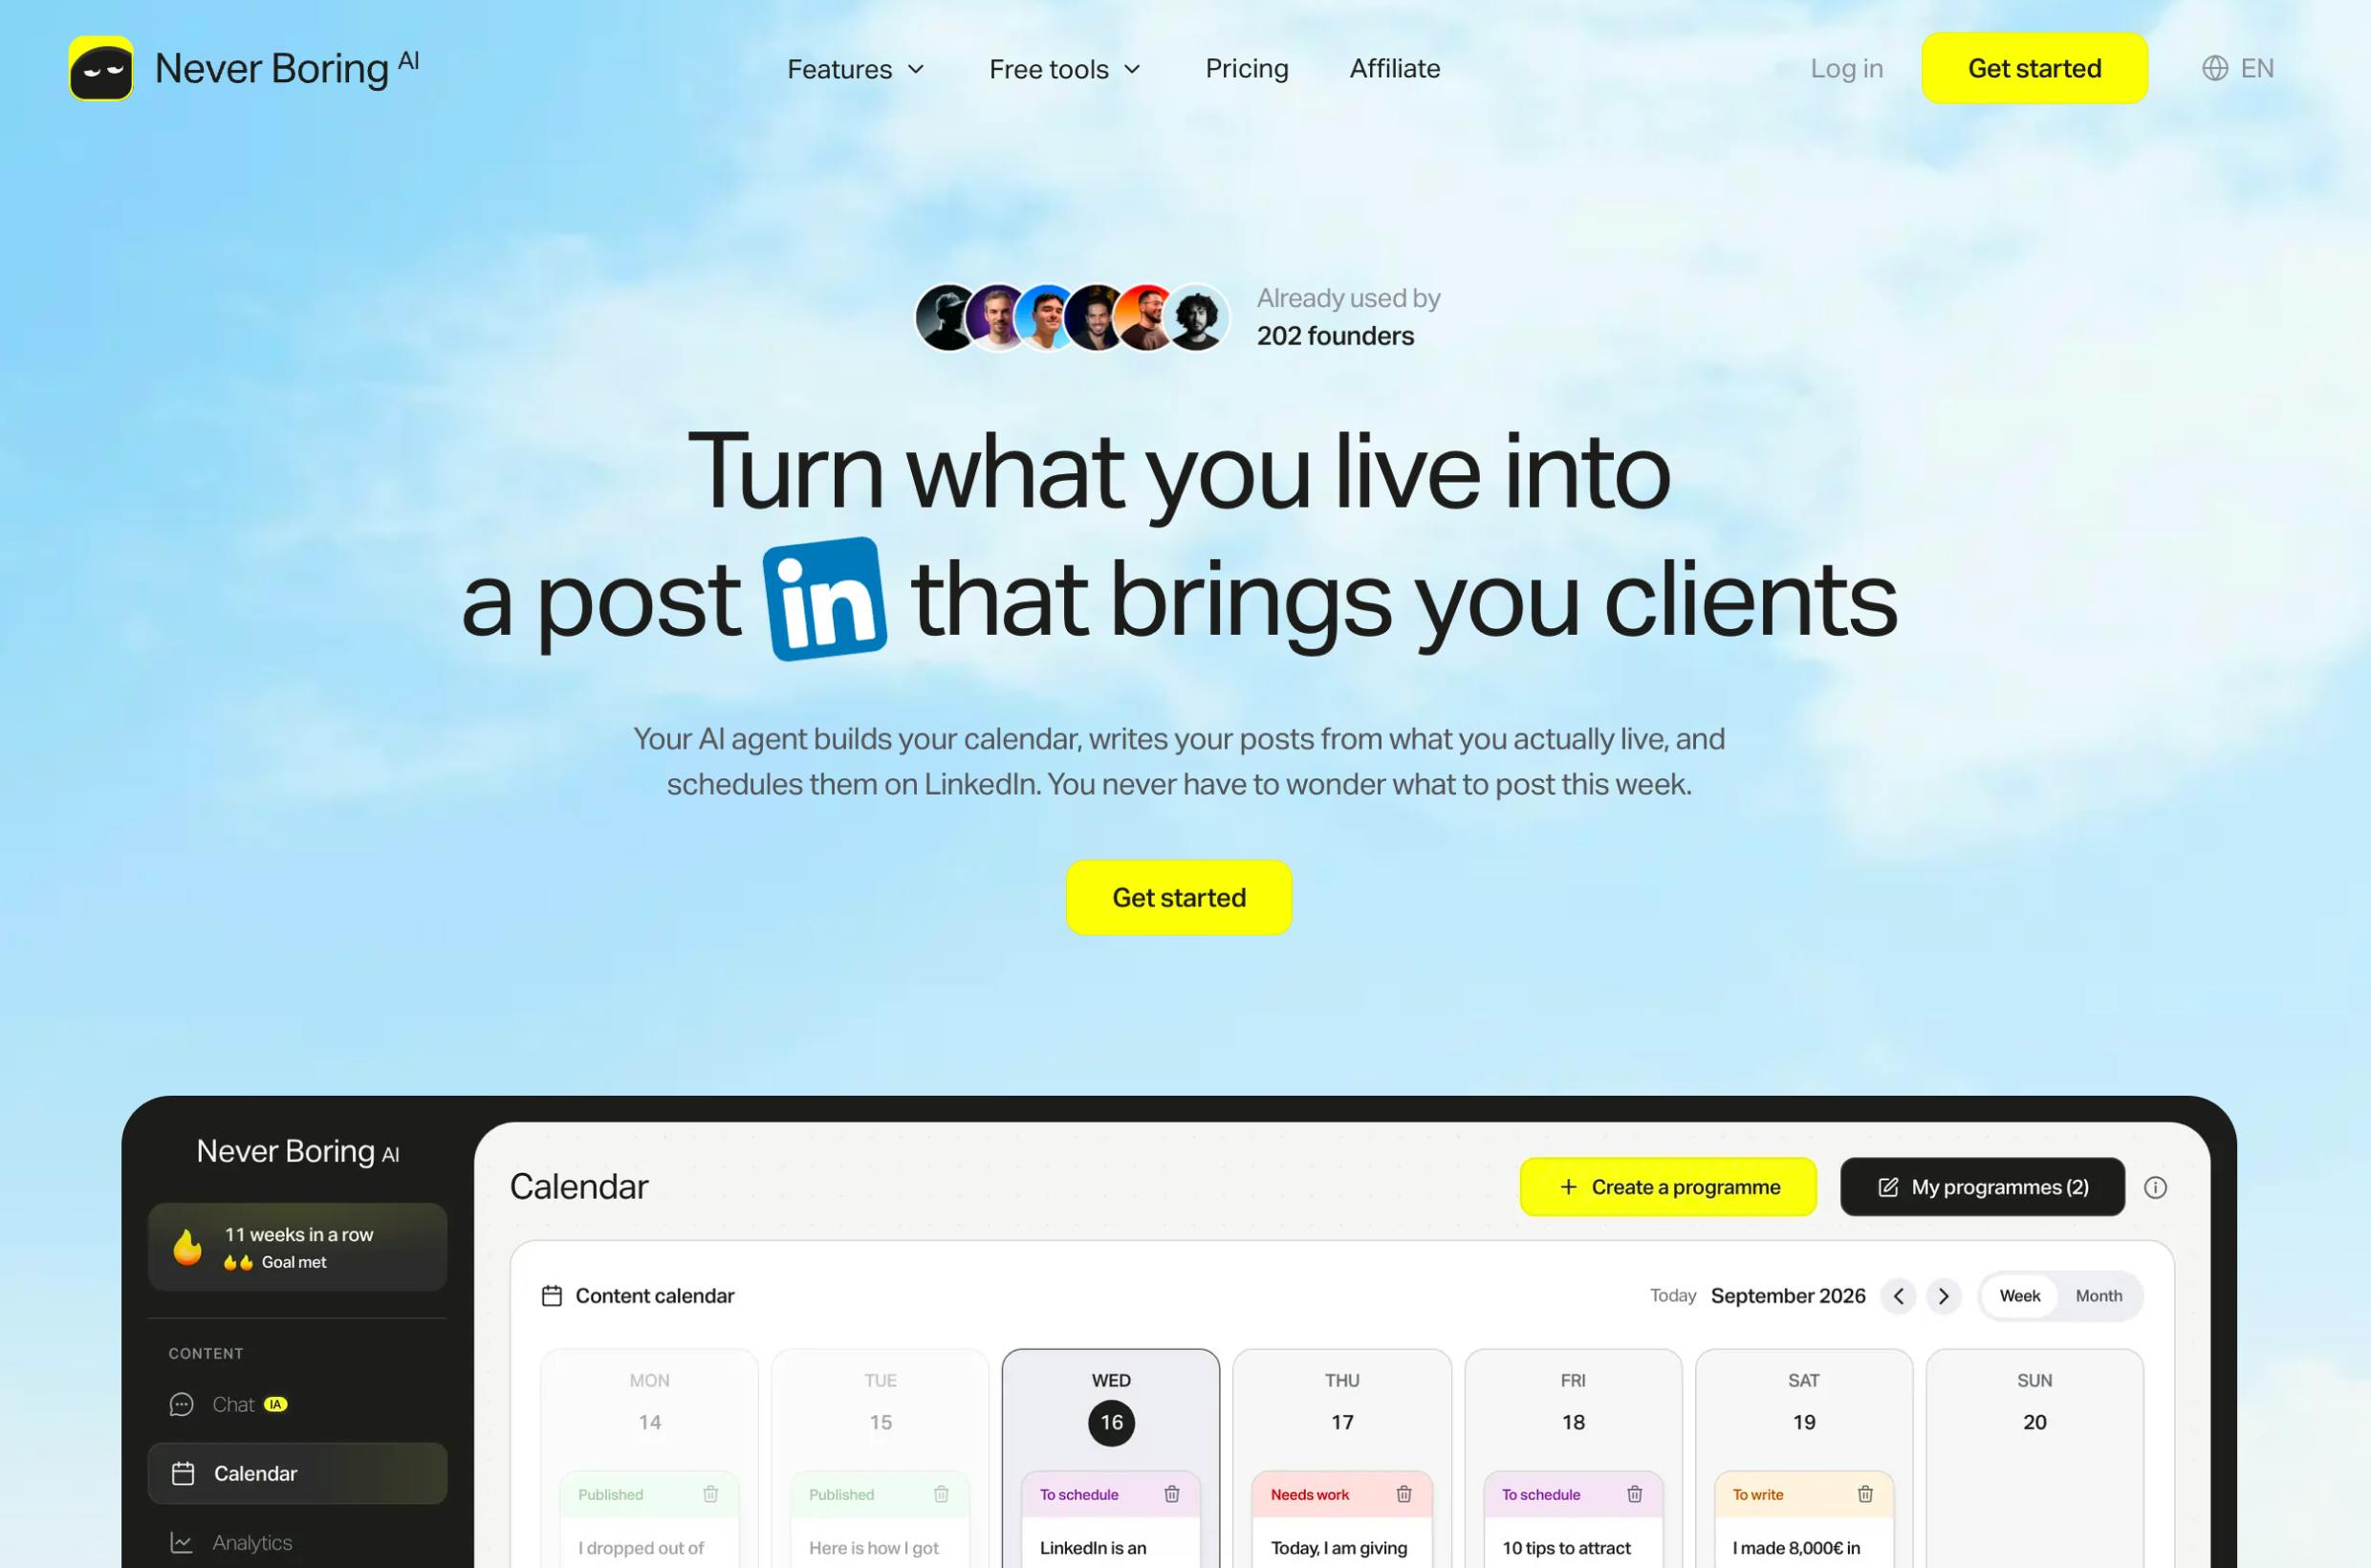
Never Boring AI is a subscription service for solo founders and independent professionals who want a steady LinkedIn publishing calendar. It interviews users about work and client stories, remembers anecdotes and writing preferences, drafts posts, and schedules approved content. Its thesis is that persistent story memory and editorial planning outperform one-off text prompts (official site; Product Hunt).
The pricing page lists $39/month or $329/year, a seven-day trial, and monthly quotas of 50 posts, five calendars, and 500 agent messages. It displays 226 founders, 644 posts, and 63 calendars; these are company-reported usage counters, not verified paid users or retention (pricing). The product merits tracking, but paid conversion and unit economics are unknown. Watch pending cohort evidence.
Company and Team
The service is published by Maxence VROILANT EI, a French sole proprietorship with a SIREN and VAT number listed in its privacy policy. Maxence is a web, product, and brand designer, runs the SHFT studio, and has roughly 11,000 LinkedIn followers (profile). He says he built the product with AI coding tools, devotes about 30% of his workweek to it, and funds it through client work; LinkedIn generates most of his freelance clients (public post; Product Hunt).
This is strong founder-problem fit and an existing distribution channel, but also means product time is limited. No employees, outside financing, or investors were found; runway and financial statements are not public.
Founder Assessment: Strong personal understanding and audience; team capacity and commercial scale remain unproven.
Product and Market Opportunity
The initial buyer is a freelancer, consultant, or solo founder who relies on LinkedIn for client acquisition but struggles to post consistently in their own voice. The product interviews the user, retains specific stories, plans several weeks of content, drafts posts, and supports scheduling, analytics, and MCP access through Claude, ChatGPT, or Cursor (pricing; MCP feature).
Its differentiator is an anecdote bank that can resurface specific experiences months later, rather than only storing a tone profile. That is a plausible product advantage but needs proof in lower edit rates, consistent publishing, or business outcomes. The company identifies Supergrow as its closest rival; its own comparison says both interview users, while Never Boring emphasizes persistent stories and French support. The comparison is self-published, not independent (comparison).
The market is narrower than all LinkedIn users: independent professionals who monetize personal-brand content. No reliable count or willingness-to-pay estimate is public. Agencies and teams could be an expansion market, but multi-profile administration is not the current core offer.
Traction and Growth Signals
The official pricing page currently displays 226 founders, 1,774 AI messages, 644 posts, 63 calendars, and 278,402 impressions. The metrics are self-reported and their definitions and attribution are not explained (pricing page). They show product activity if accurate, but do not distinguish registered, active, or paying users. The founder’s 10K-plus audience may help initial distribution.
Product Hunt showed 91 followers in the launch snapshot and questions about AI clichés, publishing, and LinkedIn API access. The maker says an external LinkedIn API supplies statistics (Product Hunt discussion). No verified MRR, paid-user count, conversion, retention, CAC, or customer acquisition outside the founder’s network was found.
Traction Assessment: A live subscription and usage counters exist; paid adoption and repeat engagement are unverified.
Competitive Position
Direct alternatives include Supergrow, Taplio, MagicPost, RedactAI, AuthoredUp, and Kleo. Supergrow lists $19/month Starter and $39/month Pro with interviews, scheduling, analytics, MCP, and team plans; Taplio lists $39–$199/month plans (Supergrow pricing; Taplio pricing). Users can also combine ChatGPT or Claude with LinkedIn’s native scheduling.
Never Boring’s proposed edge is durable first-person memory and an editorial arc. Competitors can add similar memory or interview features, so the moat is weak absent better retention or business outcomes. The service depends on LinkedIn publishing/analytics access, Anthropic models, and a third-party LinkedIn connection provider. LinkedIn may change API access or policies and disrupt core features.
If LinkedIn or a larger competitor adds persistent voice memory and scheduling, Never Boring needs to show better consistency or business results and retain the customer’s trust. Public comparative outcome data is unavailable.
Defensibility Assessment: Medium-Low
Business Model and Economics
The subscription is $39/month or $329/year, with a seven-day trial and quotas of 50 posts, five calendars, and 500 messages monthly (pricing). At monthly list price, full-year gross billings are $468 per user before tax, discounts, fees, churn, and AI costs.
The privacy policy says the service uses Anthropic Claude and providers including Supabase, Vercel, Stripe, Unipile, PostHog, and Resend (privacy policy). Quotas may contain inference costs, but cost per subscriber and gross margin are undisclosed. Founder-led distribution may lower CAC, but that has not been demonstrated. Annual onboarding and priority support add value while consuming founder capacity.
Unicorn Path
At an illustrative 10× ARR multiple, a $1 billion valuation requires about $100 million ARR. At $39/month, roughly 214,000 full-price, year-round subscribers would generate $100 million in gross billings before tax, discounts, churn, and payment costs. The current 226-user counter does not distinguish paid accounts, so the required scale is far beyond verified adoption.
A credible path needs global distribution, strong retention, team or agency revenue, and expansion beyond LinkedIn. Without these, this is more likely to become a small profitable SaaS than a venture-scale company.
Unicorn Path: Conditional
Valuation Assessment
No funding, valuation, or financing terms are public. Published pricing signals a customer price, not company value. Valuation Attractiveness: Not Assessable. Needed data includes paid users, MRR/ARR, growth, churn, gross margin, CAC, founder time and salary, and proposed terms.
Key Risks
- Usage counters may not convert to paid subscribers or retention.
- LinkedIn tools are crowded and core AI writing features are easy to copy.
- LinkedIn API or policy changes could block publishing or analytics.
- Generic or inaccurate posts may harm users’ professional reputation.
- The service stores work stories, drafts, profile data, analytics, and publishing credentials.
- Its privacy policy says user content and memory may be processed by Anthropic; LinkedIn connection and analytics rely on Unipile. No independent security assessment was found.
- A part-time solo founder may struggle to maintain integrations, security, support, and product development.
Final Assessment
Venture Potential: 62/100
| Category | Score |
|---|---|
| Market Size and Expansion Potential | 14/20 |
| Traction and Growth Evidence | 9/20 |
| Founder and Team | 8/15 |
| Product Strength | 8/10 |
| Distribution Potential | 11/15 |
| Business Model and Economics | 7/10 |
| Defensibility | 5/10 |
| Total | 62/100 |
Strengths are clear founder-problem fit, a live subscription, story memory, and founder-led reach. Gaps are paid traction, retention, and a path beyond solo professionals.
Evidence Confidence: 62/100
Product, legal publisher, pricing, privacy disclosures, and public counters are visible in primary sources. Usage figures and testimonials are company-reported. Paid-user count, revenue, growth, retention, CAC, margin, and customer outcomes remain unknown. Privacy claims are not an independent audit.
Final Decision: Watch
The product has a plausible small-business subscription model and is more developed than a concept-stage launch. Investment is premature without paid-cohort evidence and unit economics. Reassess when the founder can show retained subscribers beyond his existing audience.
Upgrade Conditions
- Report paid subscribers, MRR/ARR, conversion, churn, and cohort retention.
- Show users publish consistently and renew after six months.
- Demonstrate acquisition beyond the founder’s own LinkedIn network.
- Disclose margin after model, LinkedIn connection, hosting, and payment costs.
- Validate agency or team demand and seat expansion.
Downgrade Conditions
- The 226-user counter does not convert to paid use.
- Users stop publishing after initial setup.
- LinkedIn changes impair publishing or analytics.
- Drafts require extensive rewriting or damage user trust.
- Security or data-handling problems emerge.
Questions for Further Diligence
- Of the 226 users, how many are active, paying, trialing, or internal accounts?
- What are MRR, ARR, growth, conversion, refunds, and paid churn?
- What are 30-, 90-, and 180-day retention rates?
- How many generated posts are approved and published?
- What are CAC and conversion by channel?
- What are Claude and Unipile costs per subscriber and gross margin?
- Which LinkedIn API permissions are used, and what is the fallback if they change?
- How are stories, tokens, and agent memory encrypted, retained, and deleted?
- Do memory-based drafts outperform one-off tools in edit rate or inbound leads?
- How much founder time goes to engineering, support, and onboarding?
- What agency/team features have been requested, and what will customers pay per seat?
- Is financing planned, and what are ownership and runway?