
Table of Contents
Venture Investment Research Report: Figma Agent
Product Hunt launch date: 2026/10/07
Company: Figma, Inc. (NYSE: FIG)
Product: Figma Agent, an AI agent embedded in Figma Design
Category: Design collaboration, product development software, generative AI
Geography: Global
Company status: Publicly traded; not a standalone startup or separately valued security
Market capitalization: Approximately $11.99 billion as of October 9, 2026
FY2026 revenue guidance: $1.463–$1.467 billion
Final Decision: Watch
Venture Potential Score: 84/100
Unicorn Path: Already public; market capitalization is above $1 billion
Valuation Attractiveness: Fair to full; approximately 8.2x FY2026 guided revenue
Evidence Confidence: 82/100
Executive Summary
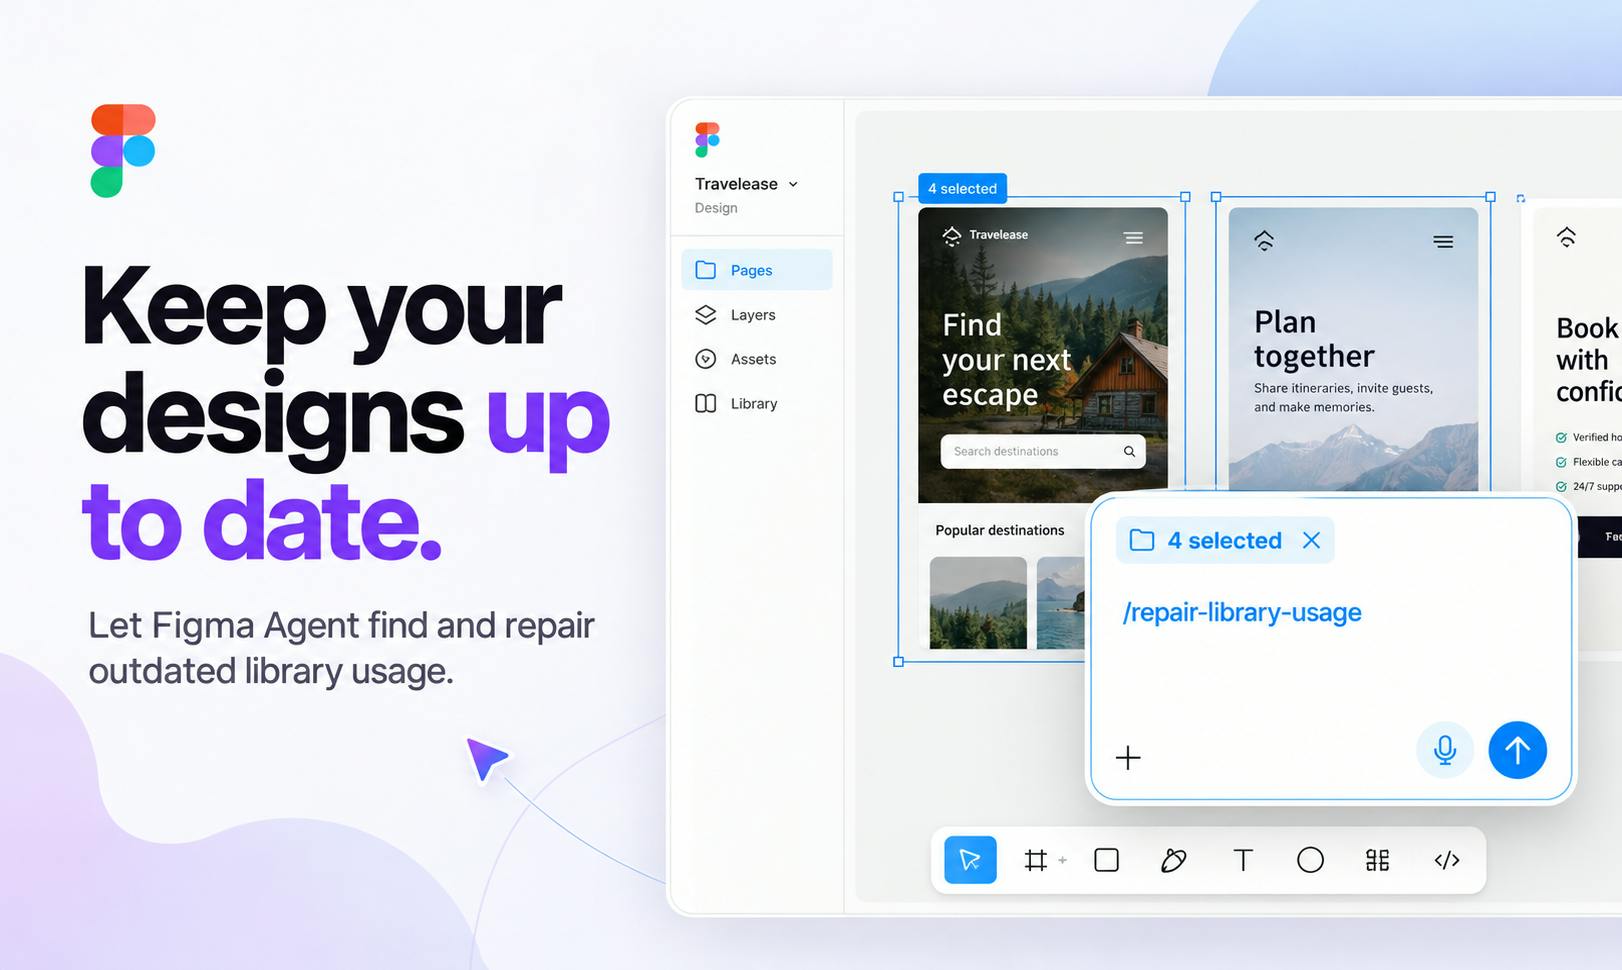
Figma Agent works inside the design canvas using customer components, variables, libraries, and files. It generates and revises editable design layers, performs bulk edits, and supports prototyping. It extends Figma’s platform; it is not a separate company. Figma Agent launch · Figma product announcement
The Agent reached general availability on October 6, 2026, with AI-credit billing starting at GA. Credit use varies by prompt, actions, and context; customers can buy extra credits by subscription or pay as they go. Agent-specific adoption, revenue, and cost data are not public. Release notes · AI credit FAQ
Parent fundamentals are strong: Q2 2026 revenue grew 48% to $370.1 million, net dollar retention was 136%, GAAP gross margin was 84%, and Figma had 15,964 customers above $10,000 ARR. Management guided to about $1.465 billion in FY2026 revenue. These metrics show platform strength, but not Agent-specific product-market fit. Q2 2026 results
At an approximately $11.99 billion market capitalization on October 9, 2026, the equity trades around 8.2 times management’s FY2026 revenue midpoint. The price reflects a high-growth, high-quality platform, while the Agent’s incremental economics remain unproven. The appropriate decision for this launch is Watch: track paid credit use and retention after GA, while recognizing that investors buy the whole public company rather than this feature alone.
Product and Customers
The Agent lives in Figma Design, works within the canvas, and can reference the team’s real libraries and design context. Figma describes use cases such as exploring multiple layout directions, editing typography or components across many screens, applying a design system, filling frames with realistic content, and maintaining library documentation. Teams can observe agents working on the canvas together. Figma Agent product details · October GA release
The likely buyer is an existing Figma team seeking faster design exploration and repetitive production work. Value depends on editable quality, system consistency, and cycle-time savings without added review. For current customers, distribution friction is low.
Team and Company
Figma was co-founded by CEO Dylan Field and Evan Wallace. Its collaborative platform serves designers, developers, product managers, and other product teams; its files, libraries, plugins, and integrations provide a base for embedding AI. Figma 2025 Form 10-K
The platform has expanded into FigJam, Slides, Dev Mode, and Make. Figma’s filings flag AI competition, packaging changes, and weak uptake of new products as risks. Field’s multi-class voting control matters to public shareholders.
Market and Bottom-Up Opportunity
The immediate market is Figma’s existing design and product teams. An illustrative scenario: 16,000 large customers, 25% paid-Agent adoption, and $25,000 in annual incremental credit spend per adopter would yield $100 million of annualized revenue. This is not a forecast; actual adoption and spend are undisclosed.
At about $1.465 billion of guided FY2026 revenue, Agent is an expansion opportunity in a larger subscription business. Its strategic value could include stronger retention and seat growth as teams adopt AI design and coding tools.
Traction and Distribution
Product Hunt lists the Agent at #6 of the day with 183 points in the launch listing. This measures launch interest, not recurring paid use. Figma’s more meaningful distribution advantage is its existing customer base, collaborative file format, and library context. The company reported 136% net dollar retention among paid customers above $10,000 ARR and 15,964 customers in that cohort, growing 34% year over year. Product Hunt listing · Q2 results
The financial results showed Figma’s first full quarter of AI-credit monetization, but the Agent only began consuming credits at GA on October 6. Thus, the Q2 figures do not yet establish this feature’s paid conversion, customer retention, or contribution margin.
Competition and Defensibility
Figma competes with Adobe, Canva, AI-first design tools, and coding agents. Its edge is access to editable components, variables, libraries, and collaborative files already used by teams; these can create workflow switching costs.
If competing tools use the same context and generate equally editable work, the advantage may narrow. Defensibility depends on reliable system-aware output and collaboration. Figma’s annual filing flags AI competition and the possibility that AI could reduce demand for interface design.
Business Model and Economics
The Agent consumes Figma AI credits. Existing seats include a monthly allowance; teams that use AI regularly can add credits through subscription or pay-as-you-go billing. Credit use varies with the agent’s actions and the context provided. The public materials reviewed do not specify Agent revenue per task, average cost, credit conversion, or gross margin. AI credit FAQ
Parent economics are attractive: Q2 GAAP gross margin was 84%, non-GAAP gross margin 85%, and non-GAAP operating margin 10%. The company had $1.7 billion of cash and marketable securities at June 30. These figures support Figma’s capacity to invest, but Agent inference costs and incremental margins may differ from the existing subscription base. Q2 2026 results
Unicorn Path, Valuation, and Risks
Unicorn path: Already achieved at the parent-company level. Figma is public, with an estimated $11.99 billion market capitalization as of October 9, 2026. The Agent has no separate valuation. Management’s FY2026 revenue midpoint is approximately $1.465 billion, implying about 8.2x market capitalization to guided revenue. This is a rough price-to-sales measure, not enterprise value or a full valuation model. Market-capitalization data · FY2026 guidance
Valuation attractiveness: Fair to full. The multiple may be supported by 48% reported quarterly growth, strong gross margins, and 136% net retention, but it leaves less room for an AI feature whose monetization has only just begun. A sustained growth slowdown or weak AI-credit attachment could pressure the multiple.
Key risks include: (1) Agent output needs too much manual correction; (2) users exhaust free credits but do not purchase more; (3) inference costs make incremental margins unattractive; (4) AI-generated interfaces reduce the need for traditional design workflows; (5) Adobe, Canva, or coding agents reach comparable quality; (6) teams limit AI use over privacy or intellectual-property concerns; (7) Figma’s packaging changes create customer friction; and (8) founder voting control limits public shareholders’ influence.
Score and Decision
| Dimension | Score |
|---|---|
| Market size and expansion | 18/20 |
| Traction and commercial proof | 18/20 |
| Team and execution capacity | 13/15 |
| Product quality and differentiation | 8/10 |
| Distribution and platform fit | 14/15 |
| Business model and unit economics | 7/10 |
| Defensibility | 6/10 |
| Total | 84/100 |
Evidence confidence: 82/100. Public filings, results, and release notes verify company fundamentals and feature mechanics. Agent-specific adoption, costs, and outcomes are not yet reported.
Final Decision: Watch. Figma is a high-quality public software platform with strong growth, retention, and distribution. The Agent is strategically well placed, but it is too early to underwrite incremental revenue or margin from this feature. At roughly 8.2x guided sales, wait for post-GA usage and paid-credit evidence before upgrading the feature-driven thesis.
Upgrade toward Invest if: paid Agent usage grows across enterprise customers; teams report reduced design-cycle time and sustained weekly use; incremental credit revenue carries healthy margins; and the valuation remains reasonable against forward growth.
Downgrade toward Pass if: usage remains trial-only, customers reject credit pricing, outputs require substantial rework, or AI-first alternatives weaken Figma’s seat growth and retention.
Diligence Questions
- What share of weekly active Figma Design users use the Agent after GA, and how does that compare across plan tiers?
- What proportion of Agent users purchase additional credits, and what is average annual credit spend per paid account?
- What are inference cost, contribution margin, and gross margin per Agent task at typical and heavy usage?
- Does Agent use increase seat expansion or net retention, and can Figma separate that effect from other AI products?
- How much editing or correction do designers need before generated layers are production-ready?
- Which repeatable workflows show measured time savings, and how were those results validated?
- How are customer files, prompts, and connected third-party data handled for training, retention, and access control?
- How does Agent quality compare with Adobe, Canva, and code-first tools on real design-system tasks?
- What are the current stock-based compensation, fully diluted share count, and expected dilution from employee awards?
- How should investors weigh the CEO’s multi-class voting control when assessing governance and capital allocation?