
Table of Contents
Viso Now Investment Report
Category: No-code / AI application builder for computer vision (agentic “vibe coding” for vision AI)
Company Stage: Seed-stage (second product from viso.ai, founded 2018)
Founder or Founders: Gaudenz Boesch (Co-CEO, Co-Founder) and Nico Klingler (Co-CEO/CTO, Co-Founder) of viso.ai
Headquarters: Schaffhausen, Switzerland; additional offices in London, UK and New York, US linkedin
Funding: $9.2 million seed round led by Accel, announced October 2023; angels include Mehdi Ghissassi (Google DeepMind), Mihai Faur (UiPath), Remy Lazarovici (Celonis), James Isilay (Cognism), and Stef van Grieken (Cradle) viso
Business Model: Freemium usage-credit SaaS (consumer/SMB self-serve) plus enterprise licensing via sibling product Viso Suite
Product Hunt Launch Date: September 10, 2026 (ranked #12 that day; ~103 upvotes, ~21 comments; promoted listing) producthunt
Report Date: September 13, 2026
| Investment Metric | Assessment |
|---|---|
| Venture Potential | 59/100 |
| Unicorn Path | Conditional |
| Valuation Attractiveness | Not Assessable |
| Evidence Confidence | 62/100 |
| Final Decision | Watch |
Executive Summary
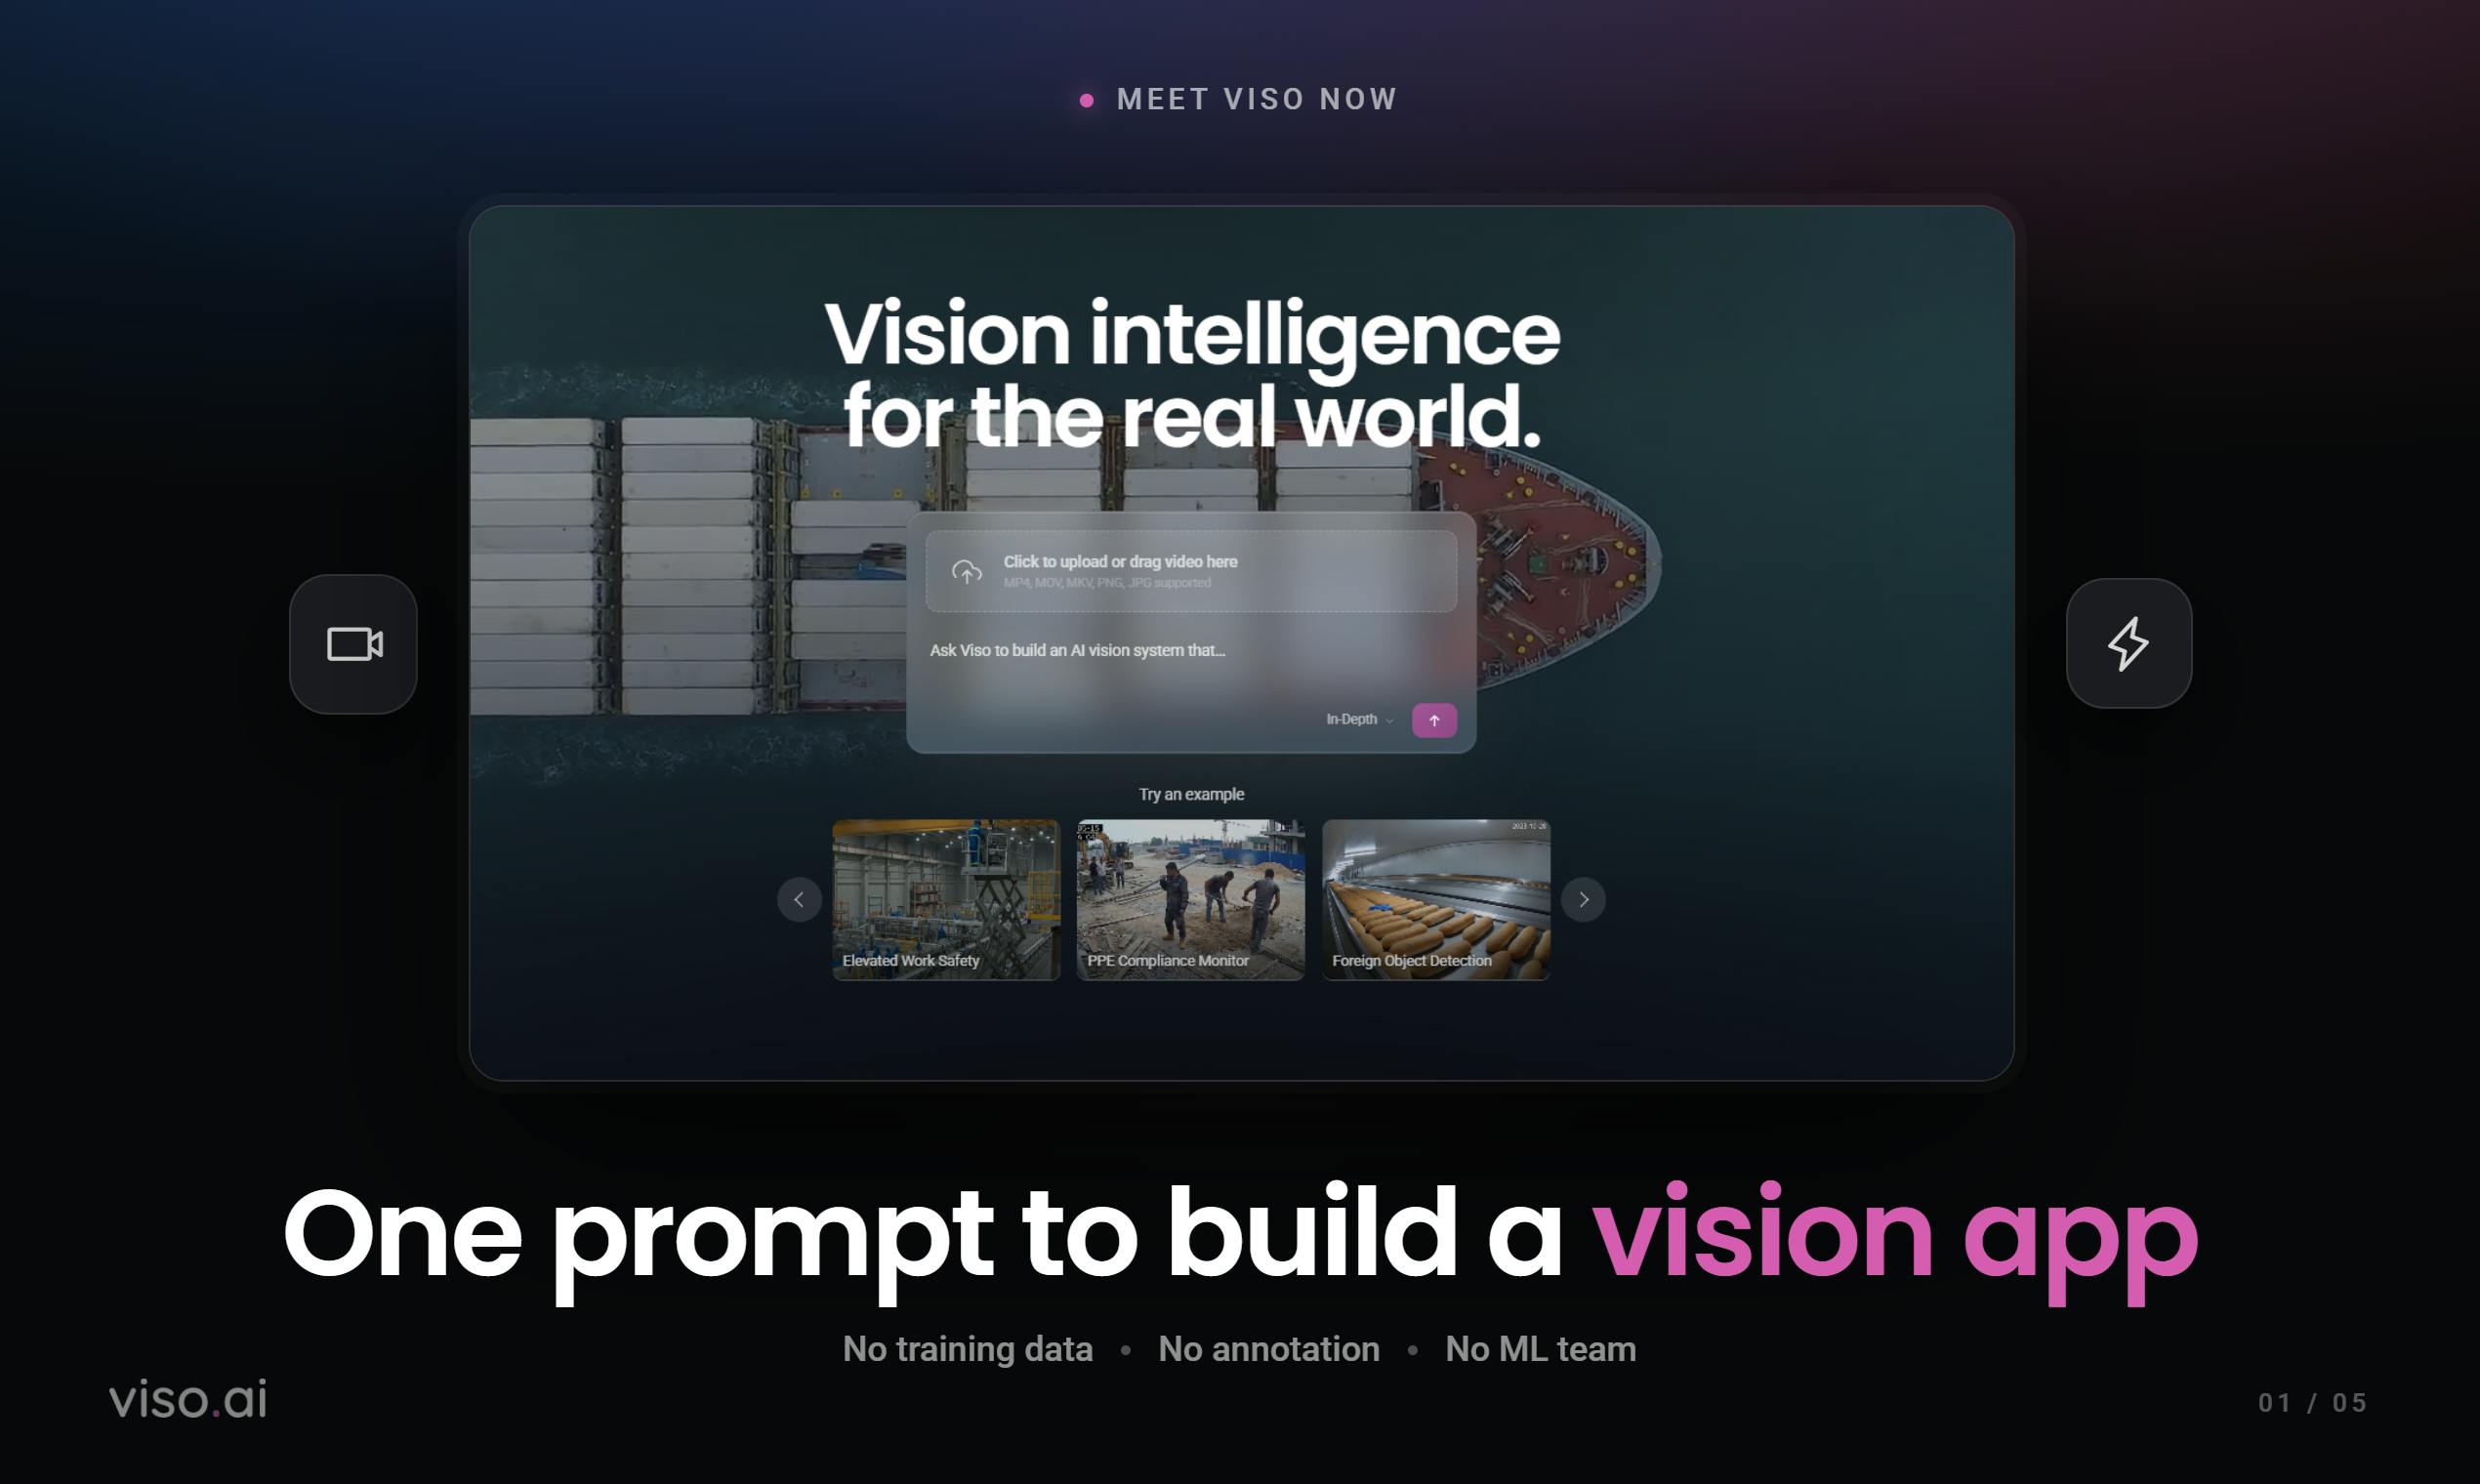
Viso Now is a self-building computer vision platform from Swiss company viso.ai. Users describe what they want to detect or understand in images, video, or live camera feeds, and the system generates the vision logic, review queues, alerting, and live dashboards — without model training, annotation, or code. It is the company’s second product, sitting below its enterprise platform Viso Suite, and is positioned as a free-to-start, prompt-driven on-ramp to applied computer vision. producthunt
The company behind the product is more substantive than a typical Product Hunt launch. viso.ai has operated since 2018, raised a $9.2 million Accel-led seed round in 2023, maintains an identifiable team of roughly 15–20 people across Switzerland, London, and New York, and lists partnerships with Intel and the NVIDIA Inception program. The enterprise product, Viso Suite, reportedly carries base workspace licensing of $49k–$99k, implying a genuine B2B revenue engine may exist beneath the new freemium product. linkedin
The strongest positive investment signal is the combination of an experienced, venture-backed team with eight years of computer vision focus and a credible wedge: converting an expensive custom-engineering category into a prompt-to-application workflow at very low entry pricing. The most important concern is commoditization — the product’s core value depends on vision-language-model reasoning that OpenAI, Google, Roboflow, Landing AI, and open-source stacks can increasingly replicate, and Viso Now’s self-serve price points ($25–$50/month) are far below what a unicorn revenue base requires. viso
The company reports over 1,000 users and 3,500 applications built on Viso Now since launch, but these figures are company-reported, unaudited, and say nothing about retention or paid conversion. Revenue, churn, conversion, and any post-2023 valuation are not publicly disclosed. The final decision is Watch: the product and team are credible, but commercial validation of Viso Now is absent and the venture-scale path depends on enterprise expansion that has not yet been demonstrated publicly. startupticker
Product Overview
Viso Now addresses the “last mile” problem of computer vision: a model can flag an event, but someone still has to route detections into a human-reviewable workflow, set thresholds, and surface results to operations staff. Traditionally this glue is custom-built per project, taking months and specialist engineers. viso
The product lets a user point it at footage or a camera feed, describe the desired outcome in natural language, and receive a working application with review queues, alerting, and business-facing dashboards, plus output connectors (webhook, MQTT) to other systems and agents. Target users are operations, QA, and safety teams — not data scientists — with cited pilots ranging from production-line defect detection to marine-biology reef surveys. producthunt
Pricing is freemium with usage credits: a free tier of 5 daily credits (up to 30/month), a Pro plan starting at $25/month, a Business plan starting at $50/month with shared credits across unlimited users, and custom enterprise pricing based on company size. Note a minor conflict: Capterra lists the entry paid plan at $30/month, but the official pricing page states $25/month; the official source is used. The product runs in the browser; no mobile app was identified. It replaces custom CV development, spreadsheet-and-inbox review workflows, and heavyweight platforms requiring annotation and training pipelines. viso
Founder and Team Assessment
The founders are verifiable: Gaudenz Boesch and Nico Klingler, co-founders and co-CEOs, both quoted in Intel partner materials and the company’s own pages. Gerard Corrigan serves as CTO and led the Viso Now launch commentary on Product Hunt. LinkedIn lists the company as founded 2018 with 11–50 employees, and the careers page shows a named team of roughly 15–20 across engineering, marketing, sales, finance, and legal. linkedin
Team composition shows genuine go-to-market investment — SDRs, an account executive, VP marketing, legal counsel — which is unusual for a company this size and suggests real commercial activity in Viso Suite. Prior exits and detailed founder résumés are not publicly disclosed. Key-person risk is moderate: two co-CEOs reduce single-founder risk, but the technical differentiation story is closely tied to the founding team’s vision-research claims. Founder-market fit is strong on paper — eight years focused exclusively on applied computer vision. viso
Founder Assessment: Strong, verifiable domain commitment and an unusually complete early-stage team, but commercial track record and founder résumés remain unverified.
Market Opportunity
The initial segment is narrow: mid-sized operations, safety, and QA teams that already run or want camera-based monitoring (manufacturing, logistics, site security, environmental monitoring) but lack in-house ML engineering. Viso.ai’s own enterprise economics suggest these customers pay five figures per workspace — the company’s economic impact study references base Viso Suite licensing of $49k–$99k, plus add-ons. viso
A bottom-up estimate: if the realistic pool of Western enterprises and mid-market industrial/commercial operators wanting vision-based monitoring is on the order of 50,000–150,000 organizations (analyst assumption, not verified), and Viso Now converts a fraction into Suite deals averaging $30k–$60k annually, the core B2B market plausibly supports several hundred million dollars in ARR — enough for venture scale if captured. The self-serve Viso Now tier itself (at $25–$50/month) would require hundreds of thousands of paying users to matter independently, which is unlikely at these price points.
Expansion opportunities are real: edge/IoT deployment, physical-security operations, compliance monitoring, and agentic integration into enterprise workflow tools. Timing is favorable — general-purpose vision models have only recently made prompt-built vision applications feasible. However, the same timing attracts heavily funded competitors. viso
Traction and Growth Signals
Verified or company-reported signals:
- Product Hunt: ranked #12 on September 10, 2026, with roughly 103 upvotes and 21 comments; the listing was promoted, which inflates placement; ~134 followers as of the report date producthunt
- Company-reported (via press release and Startupticker): over 1,000 users and 3,500 vision applications built, median time to first application under 3 minutes startupticker
- Ecosystem validation: Intel partner showcase and NVIDIA Inception membership intel
- Team hiring across sales, marketing, and engineering, indicating an operating business viso
Not publicly disclosed: revenue, ARR, paying customer counts, free-to-paid conversion, retention, usage beyond launch claims, and any independent verification of the user figures. The 1,000-user figure was published within weeks of launch via a company press release and a startup-news summary of it; these are not independent data points. startupticker
The most important missing metrics are paying customers on Viso Now, Viso Suite enterprise contract count, and any retention or renewal data. Product Hunt placement reflects launch-day attention, not sustained demand.
Traction Assessment: Plausible and directionally positive, but commercially unverified.
Competitive Position
Direct competitors include Roboflow — which has raised $62M (including a $40M Series B in November 2024 led by GV), reports over one million engineers and 16,000 organizations including half the Fortune 100, and markets a low-code pipeline builder — plus Landing AI’s LandingLens (free tier with monthly credits), V7 Labs, and Edge Impulse. Indirect competitors are far larger: OpenAI, Google (Vertex AI/Vision), and Microsoft can expose the same vision-language reasoning via API, and any vibe-coding platform (Replit, Lovable) can orchestrate the same underlying models. Free alternatives include open-source stacks (Ultralytics/YOLO plus ffmpeg and dashboard libraries). siliconangle
Viso Now’s differentiation is the opinionated, vertical packaging: prompt-to-application, human review queues, threshold-based alerting, connectors, and dashboards oriented to operations staff rather than engineers. Its pricing is aggressive — free tier and $25–$50 entry plans against Roboflow’s and Landing AI’s credit models. Distribution advantages include the existing Viso Suite enterprise customer base and Intel/NVIDIA ecosystem visibility. producthunt
Switching costs are low at the self-serve tier: a user can rebuild an application on another platform in minutes, which is the product’s own value proposition turned against it. Proprietary data advantages are not evidenced. If Google or OpenAI shipped equivalent “describe and monitor” camera tooling within six months, Viso Now’s defense would rest mainly on workflow depth, review ergonomics, and enterprise relationships — a real but narrow moat.
Defensibility Assessment: Low-to-Medium.
Business Model and Economics
Revenue combines freemium self-serve (Free/$25/$50 plans with shared credits, then usage-based enterprise pricing) with the legacy Viso Suite enterprise licensing reported at $49k–$99k base. For a $1 billion valuation, assume a 10x revenue multiple, appropriate for a high-growth vertical AI application platform with mixed enterprise/self-serve mix (comparable to how investors value applied-AI SaaS below infrastructure-layer multiples). That implies roughly $100M in annual revenue. viso
At the disclosed self-serve price points, that would require on the order of 2–4 million Pro/Business-equivalent subscriptions — clearly implausible. The realistic path is conversion: Viso Now as a top-of-funnel engine feeding Viso Suite enterprise contracts. At a $50k average contract value, ~2,000 enterprise customers would be needed. Accounting for inference costs (video processing at scale is compute-heavy), payment processing, and support, gross margins plausibly land at 60–75% for an applied AI platform — an assumption requiring verification, since vision workloads on continuous video streams can consume significantly more compute than typical SaaS.
The key economic question is whether usage growth increases revenue faster than inference and video-processing costs — the credit model mitigates this, but free-tier abuse on video workloads is a genuine cost risk. No retention, conversion, or unit-economics data is public.
Unicorn Path
Using a 10x revenue multiple, a $1 billion valuation requires roughly $100M ARR. Given Viso Now’s consumer-grade pricing, the only credible route is funnel conversion to enterprise: Viso Now would need to become a repeatable acquisition channel for thousands of $50k–$100k Viso Suite contracts, or the company would need to add usage-based platform revenue at materially higher price points, international expansion, and probably a Series A of $20M+. This requires successfully merging the self-serve agentic product with the enterprise platform — a model change from viso.ai’s historical direct-enterprise motion, hence “Conditional” rather than “Plausible.”
Unicorn Path: Conditional.
Valuation Assessment
Known: $9.2M seed led by Accel (October 2023). A November 2025 Swiss trade-press item repeats the same $9.2M figure and investor list, indicating no confirmed subsequent round; no Series A, post-money valuation, or current fundraising terms are publicly disclosed. No revenue multiples can responsibly be applied without verified revenue. viso
Valuation Attractiveness: Not Assessable. Assessing it would require current ARR, growth rate, gross margin, retention, round size, and post-money valuation or SAFE cap.
Key Risks
- Commoditization: vision-language reasoning is rapidly becoming an API commodity from OpenAI, Google, and open-source models
- Well-funded competition: Roboflow ($62M raised) targets the same low-code CV buyer with far greater scale siliconangle
- Self-serve pricing too low to build venture-scale revenue directly; success hinges on unproven conversion to Suite contracts
- Traction claims (1,000 users) are company-reported, launch-window figures with no retention or payment data eqs-news
- Inference and video-processing costs may pressure margins at scale
- Low switching costs at the self-serve tier — the product’s speed advantage cuts both ways
- Possible strategic distraction of building a second product at seed stage, acknowledged by the team itself producthunt
- No disclosed funding since 2023; runway and financing status unknown s-ge
Final Assessment
Venture Potential: 59/100
| Category | Score |
|---|---|
| Market Size and Expansion Potential | 15/20 |
| Traction and Growth Evidence | 8/20 |
| Founder and Team | 10/15 |
| Product Strength | 7/10 |
| Distribution Potential | 8/15 |
| Business Model and Economics | 6/10 |
| Defensibility | 5/10 |
| Total | 59/100 |
The strongest elements are the market timing and the credible, venture-backed team with a genuine enterprise product adjacent to the launch. The weakest are traction verification and defensibility against both funded startups and foundation-model platforms. Per the framework, 50–64 indicates a promising but insufficiently validated venture.
Evidence Confidence: 62/100
Verified: founder identities, company entity and locations, funding round and investors, product existence and pricing, team composition, partnerships. Company-reported: user and application counts, ROI study claims, enterprise licensing ranges. Estimated: market sizes and margin assumptions in this report. Unavailable: revenue, retention, conversion, paying customers, burn, runway, and current valuation.
Final Decision: Watch
The company is more established than a typical Product Hunt debut, and the product is differentiated in packaging. But Viso Now is days old publicly, its traction is unaudited, its self-serve economics cannot independently support venture scale, and defensibility against Roboflow and foundation-model vendors is unproven. DD would be premature without commercial evidence.
Upgrade Conditions
- Verified paying customer counts and free-to-paid conversion on Viso Now above roughly 5%
- Evidence of Viso Now-sourced Viso Suite enterprise contracts (e.g., 10+ closed deals attributable to the funnel)
- Sustained post-launch usage growth over two quarters rather than launch-spike claims
- A Series A with disclosed terms and credible retention cohort data
Downgrade Conditions
- No conversion evidence within two quarters, indicating a permanently free tool
- Roboflow, Landing AI, or a foundation-model vendor shipping equivalent prompt-to-vision tooling
- Material inference-cost losses at scale
- Founder departure or product activity decline
Questions for Further Diligence
- What is current ARR split between Viso Now self-serve and Viso Suite enterprise contracts?
- How many Viso Now signups have converted to paid plans, and at what credit-consumption level?
- What are 30/90/180-day retention and app-creation rates for the 1,000+ reported users?
- How many Viso Suite enterprise customers exist, and what is net revenue retention?
- What is gross margin after video inference and cloud infrastructure costs per application?
- What is monthly burn and runway remaining from the $9.2M seed?
- Is a Series A in progress, and at what valuation and terms?
- What fraction of reported users came from launch PR versus organic channels?
- How does the Visual General Intelligence engine differ technically from calling frontier VLM APIs?
- What is the attribution model linking Viso Now to enterprise pipeline?
- What happens to application costs when customers run continuous multi-camera streams?
- What are the cap table and post-seed ownership positions of the founders and Accel?
Sources
- Product Hunt — Viso Now (launch page, founder comments) producthunt
- viso.ai — official homepage and Viso Now positioning viso
- Viso Now official pricing page viso
- viso.ai — $9.2M seed announcement, Accel-led viso
- viso.ai — team and careers page viso
- viso.ai — about page (VGI white paper context) viso
- Viso Suite economic impact study (licensing ranges) viso
- Startupticker.ch — Viso Now early adoption report (secondary, company-sourced) startupticker
- S-GE — funding coverage (secondary) s-ge
- Intel partner showcase — viso.ai intel
- viso.ai on LinkedIn (company profile) linkedin
- SiliconANGLE — Roboflow $40M Series B (competitor) siliconangle
- AI Engineer — Roboflow adoption stats (competitor) ai
- PRNewswire via EQS — Viso Now adoption release (company press release) eqs-news
- Capterra — Viso Now pricing listing (secondary) capterra