
Table of Contents
Minicart Investment Report
Category: AI-native e-commerce platform
Company Stage: Seed / early commercial
Founder or Founders: Chris Nguyen and Lee Liu
Headquarters: San Francisco Bay Area, California
Funding: Undisclosed; investors identified, but round amount and terms are not public
Business Model: Freemium SaaS, payment-processing fees, AI add-ons, and potential marketplace/affiliate revenue
Product Hunt Launch Date: September 20, 2026
Report Date: September 23, 2026
| Investment Metric | Assessment |
|---|---|
| Venture Potential | 67/100 |
| Unicorn Path | Plausible |
| Valuation Attractiveness | Not Assessable |
| Evidence Confidence | 56/100 |
| Final Decision | DD |
Executive Summary
Minicart is an AI-native commerce platform for makers, creators, and small resellers. A merchant can photograph a product, generate a listing and storefront, accept payments, create social content, manage inventory, prepare shipping, and draft customer-service responses through conversational AI agents. It is currently available in the United States through a web application (official website).
The product addresses a real usability problem: traditional commerce platforms simplify infrastructure but still require merchants to configure themes, listings, applications, marketing, fulfillment, and support. Minicart attempts to replace that configuration work with task-oriented AI teammates while retaining merchant approval before consequential actions.
The strongest investment signal is the founding team. Chris Nguyen and Lee Liu previously co-founded LogDNA, now Mezmo, a Y Combinator W15 company that subsequently raised more than $100 million. They also previously sold JobLoft to onTargetjobs. This provides unusually strong technical, fundraising, and company-building experience for a newly launched product (Minicart team page; Y Combinator; Chris Nguyen; Lee Liu).
The key concern is the difference between stores created and economically active merchants. Minicart reports that more than 4,000 stores have been built, but it does not disclose active stores, GMV, completed transactions, paying merchants, retention, or revenue (Product Hunt). A free, AI-generated store can be created experimentally, making the headline store count substantially less informative than transacting-store retention.
Minicart warrants formal diligence because the team is strong, the market is large, and payments can produce usage-linked revenue. It does not yet warrant an investment recommendation because commercial traction, unit economics, and financing terms remain unavailable.
Product Overview
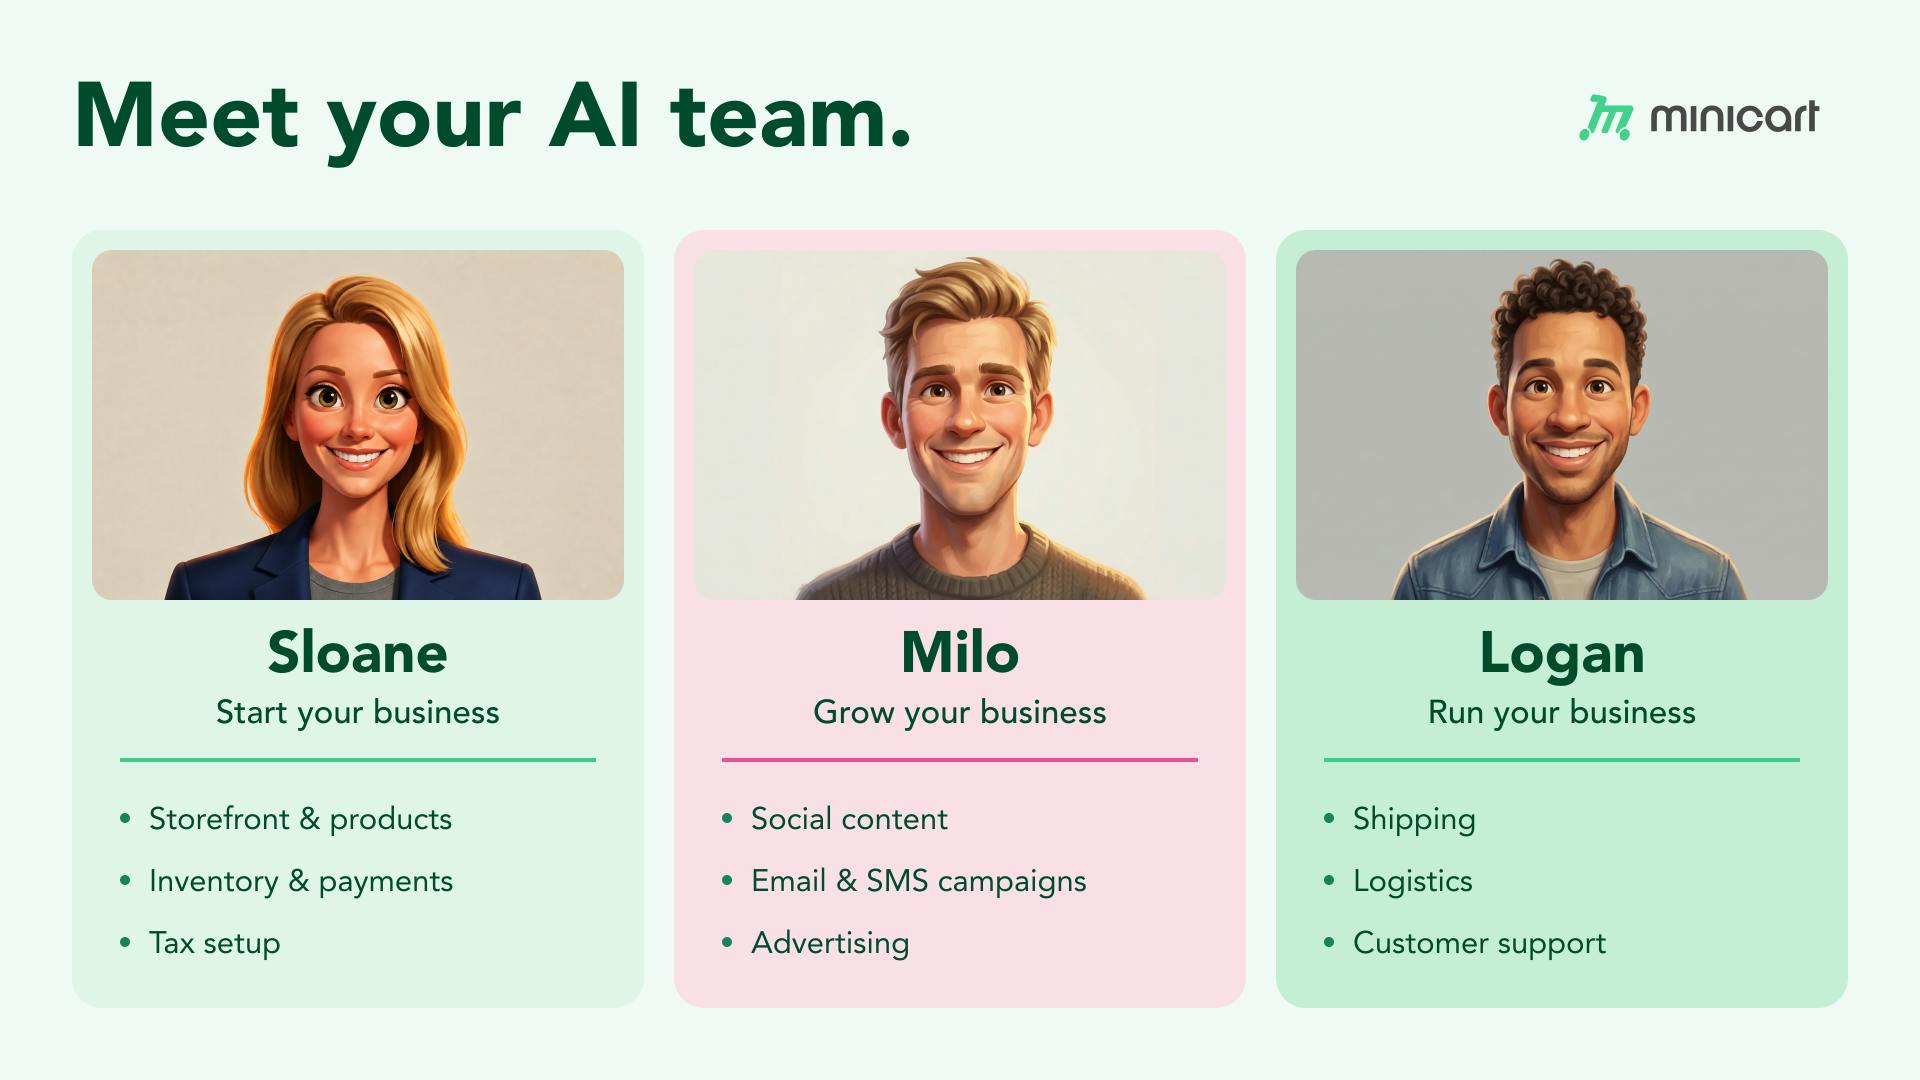
Minicart converts product photographs and short merchant instructions into product descriptions, imagery, prices, and a hosted storefront. Existing Etsy, Shopify, and eBay catalogs can be imported through read-only connections. Merchants then interact with three branded agents: Sloane for storefront management, Milo for marketing, and Logan for logistics and customer communications (official website).
The product combines storefront hosting, catalog management, payments, inventory, discounts, social publishing, shipping labels, refunds, and customer-service drafting. Minicart displays several functioning merchant storefronts, including Butterfly Boutique and Fame City Card Co., demonstrating that the storefront layer is operational.
Pricing includes:
- Free: $0, two users, up to 20 products, and 6% plus $0.30 online card pricing.
- Assistant: $19 per month list price, currently $10 per month for the first year; three users, 100 products, and 2.9% plus $0.30.
- Manager: $49 per month, five users, 250 products, and 2.7% plus $0.30.
- Director: $199 per month, 15 users, unlimited products, and 2.5% plus $0.30.
- Milo Assistant: $39 per month for recurring social content and promotional pages (pricing).
The product is currently US-only. Its main customer benefit is reducing the expertise and time required to launch and operate an independent online store.
Founder and Team Assessment
Chris Nguyen appears commercially oriented, with prior CEO, product, sales, and investment experience. Lee Liu is an experienced software architect and former CTO. Both were founders of Mezmo/LogDNA, which reached Series D, and their profiles report an earlier JobLoft acquisition (Mezmo announcement; founder profiles).
Minicart’s LinkedIn page lists five associated employees and a 2–10 employee range, consistent with a small founding-stage team, although LinkedIn headcount is not equivalent to verified full-time employment (LinkedIn). No public job listings were identified.
The founders’ repeated collaboration and prior scaling experience reduce team risk. However, their recent progression through Shuttle and Neurox before Minicart should be examined to understand product pivots, investor consent, and how prior intellectual property and financing relate to Neurox Inc., the legal entity operating Minicart.
Founder Assessment: Strong and unusually experienced founding team; current staffing, financing continuity, and full-time allocation require verification.
Market Opportunity
The initial target is US-based makers, collectors, apparel sellers, and small merchants that need an independent storefront but find established platforms too complex.
Etsy reported 5.6 million active sellers at the end of 2025, providing a relevant—though imperfect—observable pool of creator and maker merchants (Etsy 2025 Form 10-K). The broader US economy also contains 29.8 million nonemployer businesses, but many do not sell products online and should not be treated as directly addressable (U.S. Census).
An illustrative bottom-up scenario is:
- 500,000 addressable merchants across makers, marketplace sellers, and small direct-to-consumer businesses.
- $250–$700 annual net platform revenue per active merchant from subscriptions, add-ons, and retained payment economics.
- Potential initial revenue pool: approximately $125 million–$350 million annually.
These are analyst assumptions, not reported company figures. International expansion, merchant lending, advertising, fulfillment, cross-selling, and a product-discovery marketplace could expand the opportunity. The market can support venture-scale revenue, but merchant survival rates and low willingness to pay make retention difficult.
Traction and Growth Signals
Minicart’s founders reported more than 4,000 stores created before the Product Hunt launch. The launch received approximately 223 points and ranked #2 for the day according to Product Hunt’s indexed product and awards pages (Product Hunt; awards).
The company publicly showcases multiple live storefronts, including a collectibles store with a large visible catalog. This is better evidence than landing-page screenshots, but it does not establish transaction volume or retention.
The company blog shows consistent positioning and educational content from May through August 2026 (blog). No reliable independent merchant reviews, app-store metrics, public traffic data, case studies with sales outcomes, or sustained post-launch growth figures were found.
Critical missing metrics include transacting stores, GMV, revenue, paid conversion, 30/90/180-day merchant retention, cohort GMV, processing margin, and customer acquisition cost.
Traction Assessment: Credible product usage signal, but commercial quality and retention remain unverified.
Competitive Position
Direct competitors include AI-first store builders such as Genstore and established platforms adding AI functionality. Major alternatives include Shopify, Square Online, Etsy, and marketplace storefronts. Free alternatives include social selling, payment links, and manually assembled websites.
Minicart differentiates through conversational operation across storefront, marketing, and fulfillment rather than limiting AI to initial site generation. Its Etsy, Shopify, and eBay import flows can reduce adoption friction.
Pricing is aggressive. Shopify advertises online card rates starting at 2.9% plus $0.30, comparable to Minicart’s Assistant plan, while Minicart includes AI operations in the platform (Shopify pricing). However, Minicart’s free plan charges 6% plus $0.30, which may become expensive as merchant GMV grows.
Switching costs are currently modest. They could increase through transaction history, customer records, customized automation, and trained merchant context. There is no verified network effect or proprietary data advantage.
If the largest commerce platform launched equivalent conversational agents within six months, customers would stay only if Minicart remained materially easier, generated better outputs, or provided superior autonomous operations. That advantage is possible but not yet proven.
Defensibility Assessment: Medium
Business Model and Economics
Minicart combines subscription revenue with payment monetization and optional AI add-ons. Its terms also contemplate marketplace, affiliate, advertising, and usage-based fees (terms).
At current pricing, subscription ACV ranges from $228 at the standard Assistant price to $2,388 for Director, excluding add-ons. The free tier may generate revenue through the spread between its 6% card charge and underlying payment-processing costs, but Minicart’s processor contract and net retained spread are unknown.
Variable costs include payment processing, chargebacks, fraud, AI image and text generation, storefront hosting, tax services, shipping integrations, support, and customer acquisition. Small merchants can require substantial support while producing low GMV. Gross margin must therefore be measured separately for subscription, payments, and AI services.
The model becomes attractive if successful merchants upgrade and increase payment volume. It becomes less attractive if most users create free stores but never transact, or if paid plans eliminate most payment margin while retaining high support and AI costs.
Unicorn Path
An 8× net-revenue multiple is assumed for a high-growth commerce software and payments platform. This is above ordinary private SaaS valuation levels and would require strong growth, retention, and gross profit.
Required annual net revenue = $1 billion ÷ 8 = approximately $125 million.
Possible paths include:
- 250,000 monetized merchants at $500 annual net revenue each.
- 125,000 merchants at $1,000 annual net revenue each.
- Approximately $4.2 billion of annual GMV at a 3% net take rate.
The 3% example is illustrative; Minicart’s actual retained take rate is not disclosed and would be lower than the customer-facing card rate after processor, fraud, refund, and network costs.
Reaching this scale requires converting created stores into durable transacting businesses, international expansion, low-cost merchant acquisition, reliable automation, and additional monetization through marketing, fulfillment, financial services, or marketplace discovery.
Unicorn Path: Plausible
Valuation Assessment
Minicart identifies Fika Ventures, Soma Capital, Fjor, Alumni Ventures, UpHonest Capital, and other backers on its website. Fjor and Utopian Ventures separately list Minicart in their portfolios (about page; Fjor; Utopian Ventures). However, the amount, date, instrument, ownership, and valuation of the relevant Neurox/Minicart financing are not publicly disclosed.
Valuation Attractiveness: Not Assessable
Required information includes ARR, net revenue, GMV, growth, gross margin by revenue stream, retention, burn, runway, cap table, prior preferred terms, current round size, SAFE cap or post-money valuation, and liquidation preferences.
Key Risks
- Created-store count may substantially exceed active or transacting merchants.
- High churn and failure rates among micro-merchants.
- Powerful incumbent platforms can bundle conversational AI.
- Unknown payment, fraud, chargeback, support, and inference economics.
- Free-plan monetization may deter successful merchants or underserve inactive ones.
- Dependence on Stripe, social platforms, carriers, tax providers, and marketplace imports.
- AI-generated product claims, images, prices, and customer messages create legal risk.
- Terms permit certain merchant data to improve or train AI models unless available controls are used; this may concern merchants (terms).
- The privacy policy contains legacy references to calendar, location, and project-management data, creating uncertainty about current data practices (privacy policy).
- Funding and corporate continuity from Neurox are insufficiently transparent.
Final Assessment
Venture Potential: 67/100
| Category | Score |
|---|---|
| Market Size and Expansion Potential | 17/20 |
| Traction and Growth Evidence | 10/20 |
| Founder and Team | 14/15 |
| Product Strength | 8/10 |
| Distribution Potential | 9/15 |
| Business Model and Economics | 6/10 |
| Defensibility | 3/10 |
| Total | 67/100 |
The experienced founders, large merchant base, functioning product, and payments upside support the score. Weak defensibility and absent retention, GMV, and unit-economics evidence are the principal constraints.
Evidence Confidence: 56/100
Pricing, product availability, legal entity, founders, live storefronts, and prior founder experience are verifiable. Store count, investor support, and product performance are primarily company-reported. Revenue, GMV, retention, margins, financing terms, and full-time team composition remain unavailable.
Final Decision: DD
The team and market justify a founder meeting and data-room review. The decision is not Invest because valuation, retention, net revenue, unit economics, and financing terms are unknown. Formal diligence should focus on whether the 4,000 created stores represent durable commerce activity rather than low-intent experimentation.
Upgrade Conditions
- Verified growth to at least $1 million annualized net revenue.
- At least 25% of created stores becoming transacting stores.
- More than 70% six-month retention among merchants with initial sales.
- Positive contribution margin after payments, AI, fraud, and support.
- Repeatable acquisition outside founder networks and launch campaigns.
- Evidence that merchants consolidate or leave incumbent platforms.
- Clear data-use controls and updated commerce-specific privacy documentation.
Downgrade Conditions
- Most created stores never process an order.
- High merchant churn after promotional pricing ends.
- Negative contribution margin among active free-plan stores.
- Material chargeback, fraud, tax, or product-compliance losses.
- Incumbents replicate the conversational workflow without meaningful differentiation.
- Misalignment between investor claims, corporate ownership, and financing records.
Questions for Further Diligence
- How many of the 4,000 created stores are live, monthly active, transacting, and paying?
- What are current net revenue, GMV, and monthly growth by cohort?
- What are 30-, 90-, and 180-day retention rates for created and transacting stores?
- What percentage of free merchants upgrade to each paid tier?
- What net payment margin remains after processor fees, fraud, refunds, and chargebacks?
- What are gross margin and support cost by plan?
- Which acquisition channels produce the highest-quality merchants, and what are CAC and payback?
- How often are AI-generated actions rejected or materially edited?
- What assets, liabilities, investors, and employees moved from Neurox into Minicart?
- What are the current cap table, burn, runway, round size, valuation, and financing terms?
- Which merchant and buyer data are used for model training, and how does opt-out work?
- What defensible advantage prevents Shopify, Square, or another platform from matching the experience?