
Table of Contents
CC Investment Report
Category: AI-assisted household coordination
Company Stage: Google Labs experiment; not an independent startup blog
Founder or Founders: Not publicly disclosed for CC; Google names Tom Shane as a Google Labs senior product manager, not as CC’s founder blog
Headquarters: Not publicly disclosed for CC; parent Alphabet lists Mountain View, California, as its principal executive-office address sec
Funding: No separate CC financing publicly disclosed; developed within Google Labs blog
Business Model: Free experimental access is described on Product Hunt; no separate CC subscription price or revenue model is publicly disclosed labs
Product Hunt Launch Date: Exact date not publicly disclosed on the accessible listing; Google announced the household version on September 17, 2026 blog
Report Date: September 25, 2026
| Investment Metric | Assessment |
|---|---|
| Venture Potential | 41/100 |
| Unicorn Path | No Credible Path |
| Valuation Attractiveness | Not Assessable |
| Evidence Confidence | 58/100 |
| Final Decision | Pass |
Executive Summary
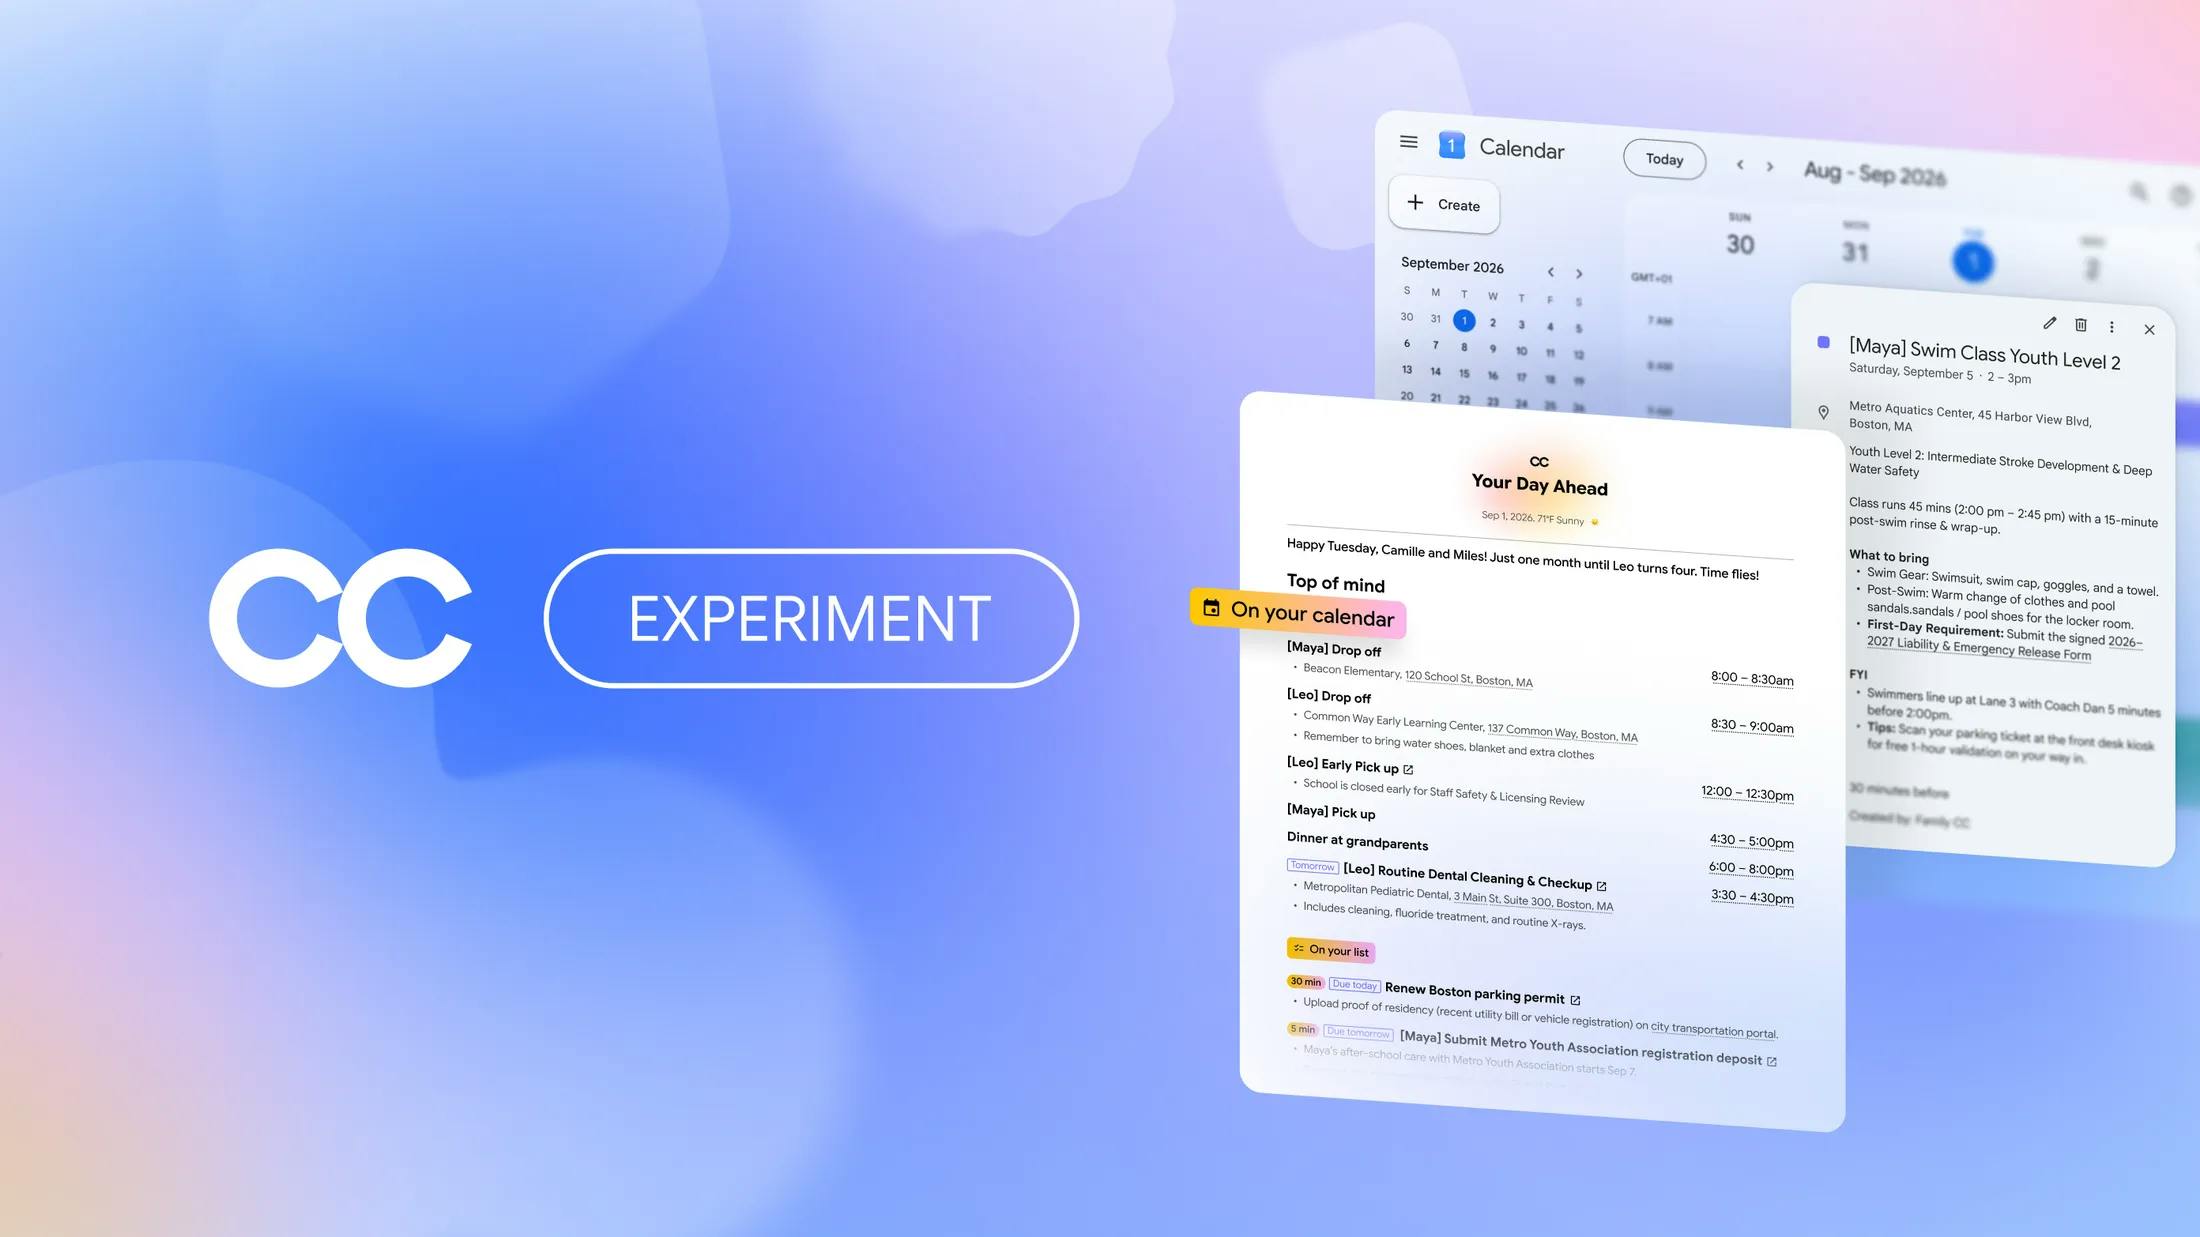
CC is Google Labs’ experimental AI agent for coordinating a household. Family members choose what information to share; CC can assemble a common daily brief, update calendars and tasks, and help with administrative jobs such as forms, lists, and meal plans. Google says the household version supports up to six members. blog
The product addresses a real coordination problem: school messages, appointments, and errands often arrive in different people’s inboxes. Its most distinctive product advantage is proximity to Gmail, Calendar, Drive, Chat, and Google’s AI infrastructure. That could reduce the work of moving information into yet another family organizer. blog
Company quality and investment access must be separated. Alphabet is an established public company with substantial resources; CC is an internal experiment, not a disclosed subsidiary offering equity to venture investors. Alphabet reported $109.9 billion of consolidated revenue in the first quarter of 2026, but that figure says nothing about CC’s users, revenue, or economics. labs
CC’s commercial evidence is thin. Product Hunt showed 119 points and a #7 daily rank when checked. Google has not disclosed CC household adoption, retention, paying users, or a product-specific price. New users face a waitlist, so even product availability is limited. blog
Decision: Pass for a direct venture-capital investment in CC. This is not a judgment that the product is poor or that Alphabet lacks resources. There is no independently investable CC company or disclosed financing opportunity to price.
Product Overview
CC aims to replace a fragmented manual routine: forwarding emails, copying event details into a shared calendar, maintaining task lists, and reminding relatives what needs doing. Google says each member can select senders or share individual messages, files, folders, and calendar information. CC then produces a “Your Day Ahead” brief and can help update shared Calendar and Tasks. Google also describes permission-based actions such as preparing forms and creating documents. These are company-described capabilities; their accuracy and time savings have not been independently established. blog
The household version is described as an early experiment on web and mobile for US adults with personal Google accounts. Existing CC users are to receive upgrade invitations, while new users can join a waitlist. Product Hunt labels the launch free, but Google has not published a separate CC paid plan or committed to future free access. There is no evidence here of a dedicated CC App Store product with ratings to assess. blog
A source inconsistency matters for assessing reach: the current CC landing-page FAQ says the waitlist is open in the United States and Canada, while Google’s dated September 17 announcement specifies the new family experience in the United States. The dated announcement is the more specific source for household availability; Canadian household access is not verified. The landing page also describes the earlier personal briefing more prominently than the new shared experience. blog
Founder and Team Assessment
Google identifies CC as a Google Labs product and credits its family-expansion announcement to senior product manager Tom Shane. That is evidence of product ownership, not a basis for calling him a founder. CC’s engineering leaders, dedicated team size, individual professional histories, previous exits, hiring plan, and long-term staffing commitments are not publicly disclosed. blog
Google’s demonstrated ability to supply account infrastructure, AI models, and consumer distribution is relevant company capability. It should not be mistaken for evidence that CC’s particular team can establish durable household engagement or that Alphabet will continue prioritizing the experiment. Google says an earlier personal CC experience was brought into the Gemini app as Daily Brief in May, underscoring that CC’s packaging can change within the parent organization. blog
Founder Assessment: Strong parent-company technical resources, but CC has no verified independent founders, team structure, or commitment suitable for startup underwriting.
Market Opportunity
The initial customer is a US household with multiple adults coordinating recurring school, care, appointment, and errand information through Google accounts. CC can offer value if it saves more effort than the family spends choosing what to share and checking the agent’s work. Its competitors’ paid plans show that some households pay for organization tools: Ohai advertises premium plans from $9.99 per month, and FamilyWall’s Google Play listing quotes $44.99 per year for US and Canadian premium users. Those prices do not establish CC’s willingness to pay. blog
A bottom-up scenario, not a market estimate, is 1 million paying households at $100 per year, yielding $100 million in annual subscription revenue before fees and service costs. The relevant number of reachable, willing-to-pay households is not verified, and CC currently has no disclosed $100 plan. At a hypothetical $60 annual price, reaching the same revenue would require roughly 1.7 million paying households.
Potential expansion includes caregivers, household purchasing, travel logistics, and more countries. Each increases the burden of permissions, accuracy, support, and local availability. A broad population of families alone does not establish a venture-scale CC business, particularly while monetization and independent ownership are absent. blog
Traction and Growth Signals
Product Hunt displayed 119 points and a #7 daily position. Its page also displays one Google Labs review that predates the family launch; it is not a reliable measure of CC household satisfaction. A maker comment describes personal use of the earlier morning email, but is not a representative retention cohort. producthunt
Google says the earlier CC became a daily habit for “many early testers” and that the family direction responded to user requests. These are qualitative, company-reported observations without a denominator, observation period, or independently verified usage measure. The September announcement and live waitlist establish continuing product activity, not commercial momentum. blog
CC-specific active households, completed tasks, task-error rates, 30- through 180-day retention, acquisition cost, revenue, and conversion are not publicly disclosed. Traction Assessment: Some early user feedback and launch interest, but household adoption and commercial traction are unverified.
Competitive Position
Ohai markets an AI household assistant with a free version and premium plans; Cozi supplies a free shared calendar, lists, and reminders; FamilyWall sells a paid family organizer. Free Google Calendar, shared email, messaging groups, and a manually maintained checklist remain formidable alternatives. blog
CC’s present differentiation is access to relevant Google workflows and its design for separately permissioned family members. Google says each CC runs on an isolated cloud computer using Gemini models and can work with Gmail, Chat, Docs, Calendar, and other Google services. That is a strong product integration advantage, though it also makes CC dependent on Alphabet’s continued support. No proprietary household dataset or independently demonstrated network effect is disclosed. blog
If the largest platform launched the same feature within six months, why would users stay? In this case Google is that platform. A rival would need to win through better cross-platform support, trust, or results; CC’s challenge is persuading every relevant household member to participate and trust its permissions. Defensibility Assessment: Medium as a Google feature, but not an independently owned venture moat.
Business Model and Economics
There is no published CC subscription, paid conversion funnel, annual contract value, or product-specific revenue. Product Hunt’s “Free” label describes the launch, while Google’s FAQ says some paid Google AI subscribers receive waitlist priority; priority is not proof that CC itself generates subscription revenue. Advertising, affiliate, transaction, and enterprise revenue should not be assumed. labs
Google describes an isolated cloud computer for each CC alongside Gemini models and actions across services. That architecture makes inference, orchestration, storage, Maps usage, security review, and support relevant variable costs, but per-household costs and margins are undisclosed. Direct web access would avoid assuming an App Store commission; any future in-app payment path would need separate fee analysis. An agent that reads household information and undertakes actions may also require substantial exception handling and support. blog
The decisive economic question is whether the value of additional retained households—or any later subscription or parent-company benefit—rises faster than AI and support costs. It cannot presently be answered.
Unicorn Path
As a counterfactual for an independent, monetized consumer subscription company, an illustrative 8× annual-revenue multiple would require approximately $125 million in annual revenue for a $1 billion valuation. At an assumed $100 per paying household per year, that means 1.25 million paying households before discounts, payment fees, churn-related acquisition expense, and AI costs. At $60 annually, it would require about 2.1 million. The multiple and prices are analyst assumptions, not CC terms or observed valuations.
That calculation is not an actual financing path. CC has no disclosed standalone equity, subscription, financial statements, or plan to separate from Google. Its integration advantage depends heavily on assets controlled by Alphabet. Alphabet’s own corporate valuation is not CC’s valuation. Until a genuine spinout or other independently investable structure exists, hypothetical household revenue does not give a VC fund a route to a $1 billion CC exit. blog
Unicorn Path: No Credible Path for CC as an independently investable company in its present structure.
Valuation Assessment
CC has no separately reported funding round, investors, SAFE cap, post-money valuation, acquisition offer, or fundraising status. Alphabet is publicly traded, but its consolidated filings do not provide a separable CC valuation or product revenue. Ohai and FamilyWall show alternative business models, not a defensible transaction multiple for this Google Labs experiment. sec
Valuation Attractiveness: Not Assessable. Assessment would first require an investable legal entity and proposed security. It would then require CC revenue or a credible monetization plan, growth, retention, gross margin, inference cost, burn allocation, intellectual-property and data-access rights, cap table, round terms, and control provisions. No responsible CC price range can be produced from Alphabet’s financial results or Product Hunt votes.
Key Risks
- No investment vehicle: CC is a Google Labs service, not disclosed as a venture-financeable company. blog
- No verified business model: Free experimental access has no disclosed CC revenue or price. labs
- Unproven household retention: Adding members and maintaining permissions may be harder than using a manual shared calendar. blog
- Sensitive-data exposure: CC handles selected emails, files, schedules, and shared memory, making permission mistakes consequential. blog
- Memory controls may surprise users: Google says deleting an original Gmail message or Drive file does not automatically remove it from CC’s memory; disconnecting is required to clear CC data. labs
- Action accuracy: Incorrect dates, forms, or logistics could create more work or cause harm. blog
- Unknown variable costs: The stated per-CC cloud-computer and model architecture has no disclosed unit economics. blog
- Parent-company priority: Google has already repackaged the personal briefing experience into Gemini’s Daily Brief. blog
Final Assessment
Venture Potential: 41/100
| Category | Score |
|---|---|
| Market Size and Expansion Potential | 12/20 |
| Traction and Growth Evidence | 2/20 |
| Founder and Team | 6/15 |
| Product Strength | 8/10 |
| Distribution Potential | 10/15 |
| Business Model and Economics | 0/10 |
| Defensibility | 3/10 |
| Total | 41/100 |
The score assesses CC as a prospective standalone venture, not Alphabet’s quality. Product integration and distribution are its strengths. The absence of an investable company, monetization, and verified product-level traction dominate the investment case.
Evidence Confidence: 58/100
Google’s dated announcement verifies the product’s stated design, ownership, and US household rollout; its live FAQ verifies waitlist terms but conflicts on geography and still foregrounds the earlier personal version. Alphabet’s public filing verifies the parent, not CC economics. User-habit statements are company-reported; the market and unicorn figures are hypothetical. Product-specific users, retention, revenue, team size, costs, and financing remain unavailable. blog
Final Decision: Pass
CC may become a useful Google product. It is not presently an independent venture investment, and neither Alphabet’s financial strength nor Product Hunt interest fixes that structural problem. Reconsideration would require an actual investable structure and evidence of durable household use and monetization; limited information alone is not the reason for Pass.
Upgrade Conditions
- Establish a legally investable CC entity or clearly defined carve-out, including rights to the product, models, data integrations, and distribution.
- Publish or furnish household activation, repeat-use, task-quality, and 30-, 90-, and 180-day retention cohorts.
- Demonstrate paid willingness, credible gross margins after AI costs, and repeatable acquisition beyond Google-owned promotion.
- Provide committed leadership, financing terms, and governance suitable for outside investors.
Downgrade Conditions
- The experiment is discontinued or folded into another product without standalone rights.
- Household participation or repeat use remains weak after general availability.
- Material permission, privacy, security, or action-accuracy incidents occur.
- Inference and support costs make a prospective paid offering uneconomic.
Questions for Further Diligence
- Is any CC spinout, outside financing, or independently investable security actually contemplated?
- Who owns the product roadmap, and how many people work on CC full-time?
- How many households are invited, activated, and weekly active under the new shared experience?
- What share invites a second member, and what are 30-, 90-, and 180-day household retention rates?
- Which actions are completed successfully, and how often must users correct or reverse them?
- What are per-household monthly inference, cloud-computer, Maps, storage, and support costs?
- Is there a proposed CC price, and what evidence supports household free-to-paid conversion?
- If monetized, what would MRR growth, gross margin, and net revenue retention look like by cohort?
- Which channels acquire retained households, and what are their fully allocated acquisition costs?
- What happens to permissions, shared memory, and previously generated information when a member leaves?
- How are CC’s burn, runway, intellectual property, and long-term founder or leadership commitment defined within Alphabet?
- If a carve-out is contemplated, what are its cap table, valuation, financing terms, and continuing Google-service rights?