
Table of Contents
Resurf Investment Report
Category: Local-first personal knowledge management / digital library
Company Stage: Early commercial; described as a bootstrapped indie project
Founder or Founders: Deep Lakhani
Headquarters: Montréal, Canada
Funding: Not publicly disclosed
Business Model: Freemium desktop software with one-time paid licenses; free iOS companion
Product Hunt Launch Date: September 14, 2026
Report Date: September 16, 2026
| Investment Metric | Assessment |
|---|---|
| Venture Potential | 48/100 |
| Unicorn Path | Conditional |
| Valuation Attractiveness | Not Assessable |
| Evidence Confidence | 42/100 |
| Final Decision | Watch |
Executive Summary
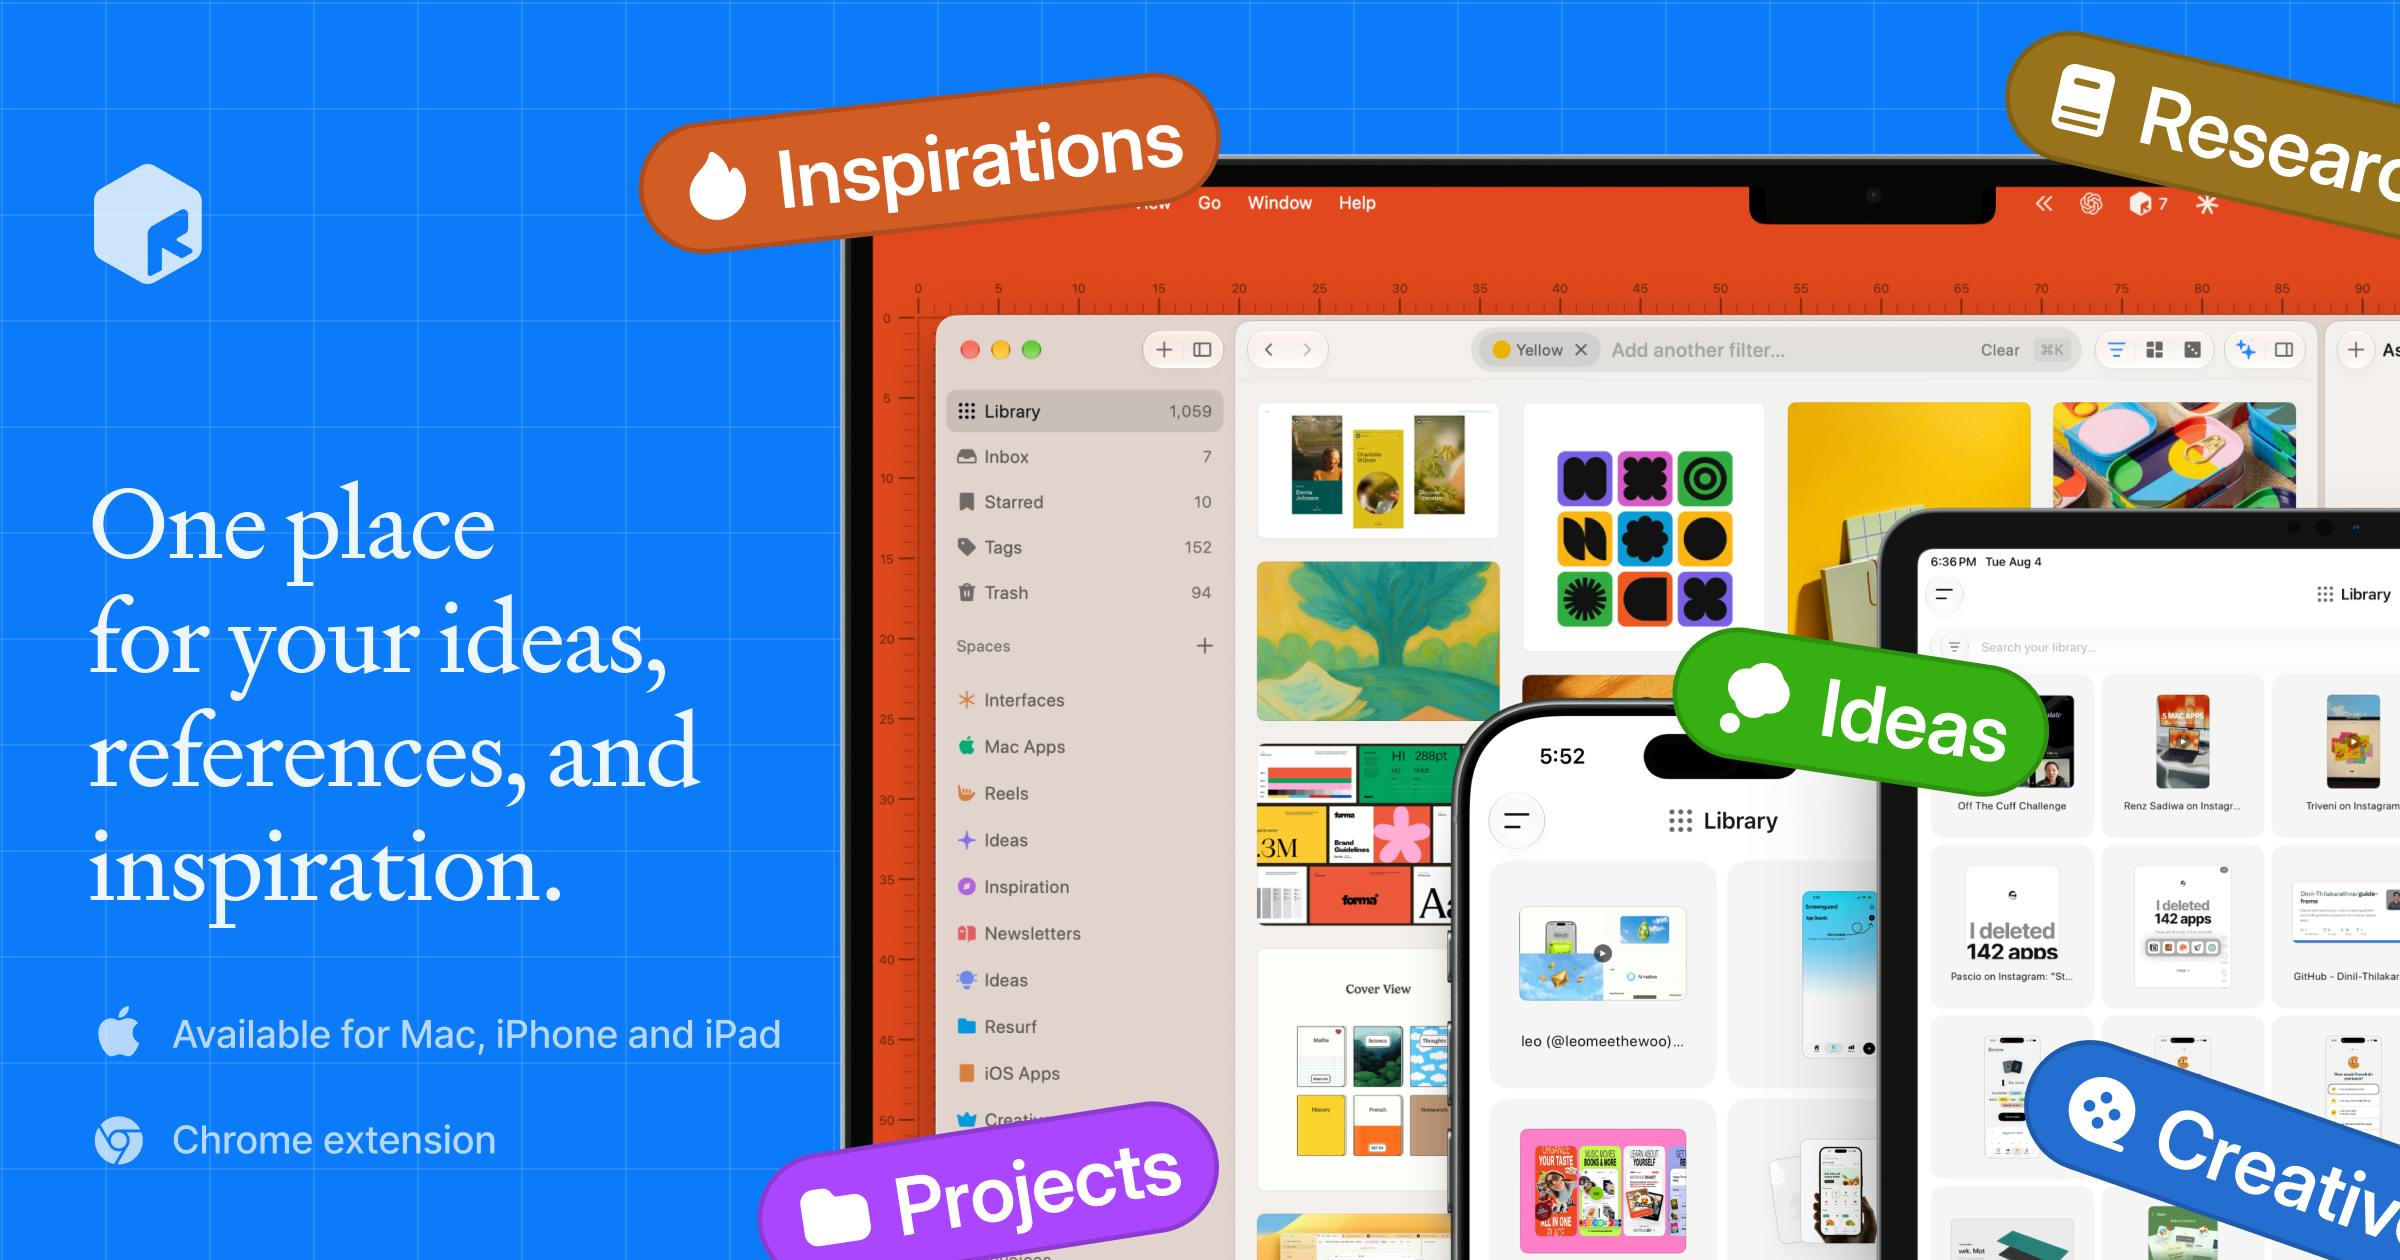
Resurf is a local-first personal context library for collecting notes, links, PDFs, images, videos, voice memos, and other reference material. It is native on Mac, iPhone, and iPad, with optional iCloud synchronization and bring-your-own-key AI features for summarization and querying saved content (official website, Resurf 2 announcement).
The initial customer is a Mac-centric designer, researcher, developer, writer, or other knowledge worker whose material is fragmented across bookmarks, screenshots, files, and notes. The strongest product attributes are privacy, file ownership, native performance, broad content support, and an upfront price rather than another subscription.
The strongest investment signal is execution speed. Founder Deep Lakhani built the original application, subsequently rewrote it from Electron into Swift, added iPhone and iPad applications, implemented iCloud synchronization, and launched a Chrome extension (founder announcement, Chrome Web Store). Resurf also ranked first among Product Hunt’s daily products on September 14, 2026, although this represents launch attention rather than product-market fit (Product Hunt leaderboard).
The principal investment concern is that no reliable public evidence establishes revenue, paid-user count, retention, growth, or repeatable customer acquisition. The one-time consumer license also limits recurring revenue and lifetime-value visibility. Competition is extensive, switching costs are low, and the founder’s portfolio says he is currently employed at Profound, leaving full-time commitment and team capacity unverified (founder portfolio).
Decision: Watch. Resurf appears capable of becoming a strong independent software business. It does not yet present enough commercial evidence or a sufficiently scalable current business model to justify formal venture due diligence.
Product Overview
Resurf addresses the gap between easy capture and useful retrieval. Users can save material through keyboard shortcuts, the Mac application, Chrome, or iOS share sheets; organize it into spaces, tags, and stacks; search the library; annotate sources; and optionally query saved context with AI (official website).
Content is stored locally, while synchronization uses the user’s private iCloud container. AI is opt-in and currently uses the customer’s own API key, with requests sent directly to the provider rather than through Resurf’s servers (privacy policy). This reduces cloud-storage and inference exposure but places setup and AI costs on users.
The Mac free tier permits 50 captures. Current introductory pricing is $39 for unlimited use and two years of updates or $79 for lifetime updates; a license covers up to two Macs. The version remains usable after the update period, and refunds are available for 14 days (pricing). The iPhone and iPad applications are described as free and unlimited (iOS page).
The product replaces combinations of browser bookmarks, screenshot folders, Apple Notes-style repositories, read-later applications, and visual asset managers. Product quality appears promising, but the newly rewritten application still has reported usability defects involving shortcuts, quitting, navigation, tag management, and sync conflict handling (Reddit launch discussion).
Founder and Team Assessment
Deep Lakhani identifies himself as Resurf’s founder and a design engineer. His portfolio places him in Montréal and lists current work at Profound and prior work at Endex and Mintlify (portfolio). Public profiles also describe full-stack engineering and product-design experience, supporting credible founder-product fit for a design-intensive native application.
Execution evidence is stronger than commercial evidence: Lakhani designed and built the product, responded publicly to bugs, and completed a substantial native rewrite. No previous exit, fundraising history, sales leadership, or scaled consumer-software outcome was verified.
Resurf calls itself a bootstrapped indie project, and public communication is primarily in the first person (download page, about page). No reliable team-size or hiring evidence was found. The founder’s current employment elsewhere raises unresolved questions about full-time commitment and key-person dependency.
Founder Assessment: Strong product and design execution, but commercial capability, team depth, and full-time commitment remain unproven.
Market Opportunity
The narrow initial segment is Apple-device users—particularly designers, researchers, developers, writers, and creative professionals—who frequently collect mixed media and prioritize privacy and local ownership.
No reliable public count exists for this specific segment. An illustrative bottom-up scenario is:
- 2–5 million realistically reachable global power users
- $40–$80 one-time revenue per purchaser
- $80–$400 million of cumulative gross license revenue at full penetration
This is an analyst scenario, not a verified market estimate, and cumulative billings are materially less valuable than recurring ARR. At a more realistic 2% penetration, the same model produces approximately 40,000–100,000 purchasers and $1.6–$8 million in cumulative gross revenue.
Adjacent opportunities include Windows, team libraries, collaborative research, enterprise knowledge management, APIs, MCP-based AI workflows, and recurring paid services. These could expand the market substantially, but collaboration, Windows support, and enterprise functionality are not current verified capabilities. The published roadmap currently emphasizes imports, browser coverage, reminders, semantic search, and related-content discovery (roadmap).
Traction and Growth Signals
Resurf ranked #1 Product of the Day on September 14, 2026. Its Product Hunt page showed approximately 421 followers and a 4.0 rating from one review at the research date (Product Hunt, leaderboard). These figures demonstrate launch interest but not commercial traction.
A January Reddit launch generated 97 points and 72 comments, while the later native-release discussion generated 113 points and 100 comments. Comments include purchase intent and at least one claimed lifetime-license purchase, but also concrete bug reports and concerns about pricing, platform availability, keyboard workflows, and sync conflicts (January discussion, native-release discussion).
The Chrome extension reached version 1.0.1 and was updated March 3, 2026 (Chrome Web Store). However, the public changelog lists only the January 11 initial release despite the later rewrite, making release cadence difficult to verify independently (changelog).
Revenue, paying customers, active users, retention, conversion, downloads, refunds, and post-launch organic growth are not publicly disclosed.
Traction Assessment: Positive launch engagement and visible development, but commercially unverified.
Competitive Position
Direct alternatives include mymind, Raindrop.io, Eagle, Anybox, and Fabric. Free or bundled alternatives include browser bookmarks, filesystem folders, and general notes applications.
Resurf differentiates through local files, private iCloud sync, native Apple applications, broad media handling, BYOK AI, and a one-time license. This compares favorably on privacy and ongoing cost with cloud subscriptions such as mymind, while Resurf’s $39 introductory license is similar to Anybox’s advertised $39.99 lifetime tier (mymind pricing, Anybox pricing). However, Raindrop offers unlimited bookmarks, collections, devices, and imports on its free plan, while Anybox already supports migration, automation, multiple views, and native Apple applications (Raindrop pricing, Anybox).
Switching costs are low unless users build substantial libraries. Local storage and exportability reduce lock-in—a customer benefit but a defensive weakness. No proprietary dataset, network effect, or exclusive distribution channel is evident.
If a large platform launched the same feature within six months, why would customers remain? The credible answers are design quality, native speed, file ownership, broad capture workflows, and founder responsiveness. These are valuable but replicable.
Defensibility Assessment: Low
Business Model and Economics
Revenue currently comes from one-time Mac licenses. The free tier supports acquisition; iOS is free, and AI costs are largely borne by customers through their own API keys (pricing, privacy policy). Direct Mac distribution avoids App Store commissions, according to the founder, while Polar handles payments and licensing (Reddit discussion, terms).
The architecture should permit high software gross margins because Resurf does not host user libraries or centrally fund AI inference. Nevertheless, verified gross margin is unavailable. Support, macOS compatibility, ongoing native development, payment processing, analytics, and license infrastructure remain variable or continuing costs.
The larger problem is revenue durability. One-time licenses create limited expansion revenue and require continuous new-customer acquisition or paid upgrades. No team, enterprise, storage, or recurring AI revenue is currently verified.
Unicorn Path
For the present non-recurring consumer-software model, a conservative 5× annual-revenue multiple is more appropriate than a high-growth SaaS ARR multiple. A $1 billion valuation would therefore require approximately:
$1 billion ÷ 5 = $200 million annual revenue
At an assumed blended net revenue of $50 per new license, Resurf would need roughly 4 million new paid licenses every year. That is not credible from the available traction.
An alternative recurring strategy could support a 10× ARR multiple if Resurf developed strong growth and retention:
$1 billion ÷ 10 = $100 million ARR
At $120 per paid seat annually, this would require approximately 833,000 paid seats. Achieving that would likely require team collaboration, enterprise administration, cross-platform support, API revenue, repeatable international distribution, and materially stronger defensibility.
Unicorn Path: Conditional
Valuation Assessment
No funding round, investors, SAFE cap, current raise, or valuation was verified. Revenue and growth are also undisclosed.
Valuation Attractiveness: Not Assessable
A responsible assessment requires current ARR or recognized license revenue, monthly growth, retention, refund rates, gross margin, burn, runway, cap table, round size, valuation cap or post-money valuation, and financing preferences.
Key Risks
- No verified revenue, retention, or active-user evidence.
- One-time pricing limits recurring revenue and predictable lifetime value.
- Low switching costs and substantial feature overlap with established alternatives.
- Founder commitment is unclear while he remains publicly employed elsewhere.
- Key-person risk appears high; no broader team is verified.
- Native rewrite still has reported workflow, bug, and synchronization issues.
- Apple and iCloud concentration restrict the current addressable market.
- Local-first architecture reduces opportunities for collaborative and enterprise monetization.
- Product Hunt and Reddit attention may not persist after launch.
- Open formats and BYOK AI improve trust but weaken lock-in and data defensibility.
Final Assessment
Venture Potential: 48/100
| Category | Score |
|---|---|
| Market Size and Expansion Potential | 11/20 |
| Traction and Growth Evidence | 5/20 |
| Founder and Team | 10/15 |
| Product Strength | 8/10 |
| Distribution Potential | 7/15 |
| Business Model and Economics | 4/10 |
| Defensibility | 3/10 |
| Total | 48/100 |
Product execution and founder-market fit are the strongest elements. Commercial traction, recurring economics, team depth, and defensibility are the weakest.
Evidence Confidence: 42/100
Verified information includes functionality, pricing, privacy architecture, founder identity, product releases, Product Hunt ranking, and public community feedback. Product capabilities and roadmap are primarily company-reported. Market sizing and unicorn calculations are analyst scenarios. Revenue, customer count, retention, growth, gross margin, funding, valuation, burn, runway, team size, and cap table remain unavailable.
Final Decision: Watch
Resurf is a promising product but currently resembles a high-quality independent software business more than a venture-scale company. Its current one-time-license model and narrow Apple-centric positioning make a billion-dollar outcome improbable without substantial strategic expansion.
Upgrade Conditions
- Verified annualized revenue above $1 million with sustained growth.
- Six-month paid-user retention or continued active use above 70%.
- Evidence of repeatable acquisition outside Product Hunt and Reddit.
- A credible recurring team, API, or enterprise revenue product.
- Verified gross margin above 80% after support and infrastructure.
- Full-time founder commitment and evidence of a complementary commercial team.
Downgrade Conditions
- Weak paid conversion or high refund rates.
- Declining release activity after the launch period.
- Persistent sync or data-integrity failures.
- Fast replication by larger knowledge-management platforms.
- Inability to expand beyond Apple-only individual users.
- Misleading traction, privacy, or funding claims.
Questions for Further Diligence
- What are current MRR-equivalent license sales and monthly gross bookings?
- How many customers have purchased each license tier?
- What are 30-, 90-, and 180-day active-use retention rates?
- What percentage of free users reach the capture limit and convert?
- What are refund rates and paid-customer cohort trends?
- Which channels generate customers, and what is CAC by channel?
- What are gross margin and ongoing support costs per active customer?
- How many hours per week does the founder work on Resurf, and when would he become full-time?
- What is the team structure, legal entity, ownership, and cap table?
- Is a recurring team or enterprise plan planned, and what validated demand supports it?
- What are the current round size, valuation, SAFE terms, and intended use of proceeds?
- How are iCloud conflicts, database corruption, backups, and security incidents tested and handled?