
Table of Contents
Epilude Notetaker Investment Report
Category: AI voice dictation and meeting-notetaking software (Mac desktop utility)
Company Stage: Bootstrapped, self-described “default alive” (company-reported, unverified)
Founder or Founders: Gustav Ek, Co-Founder (Product Hunt hunter); “Mark,” Co-Founder (surname not publicly disclosed) epilude
Headquarters: Not publicly disclosed (the hunter shares a name with a Sweden-based software engineer, but the match is unverified)
Funding: Not publicly disclosed; company states it is fully bootstrapped with no outside investors epilude
Business Model: Freemium desktop software — one-time perpetual license and optional cloud subscription
Product Hunt Launch Date: September 13, 2026 (second launch; the original Epilude dictation app launched earlier in 2026, date not confirmed)
Report Date: September 16, 2026
| Investment Metric | Assessment |
|---|---|
| Venture Potential | 45/100 |
| Unicorn Path | Improbable |
| Valuation Attractiveness | Not Assessable |
| Evidence Confidence | 50/100 |
| Final Decision | Pass |
Executive Summary
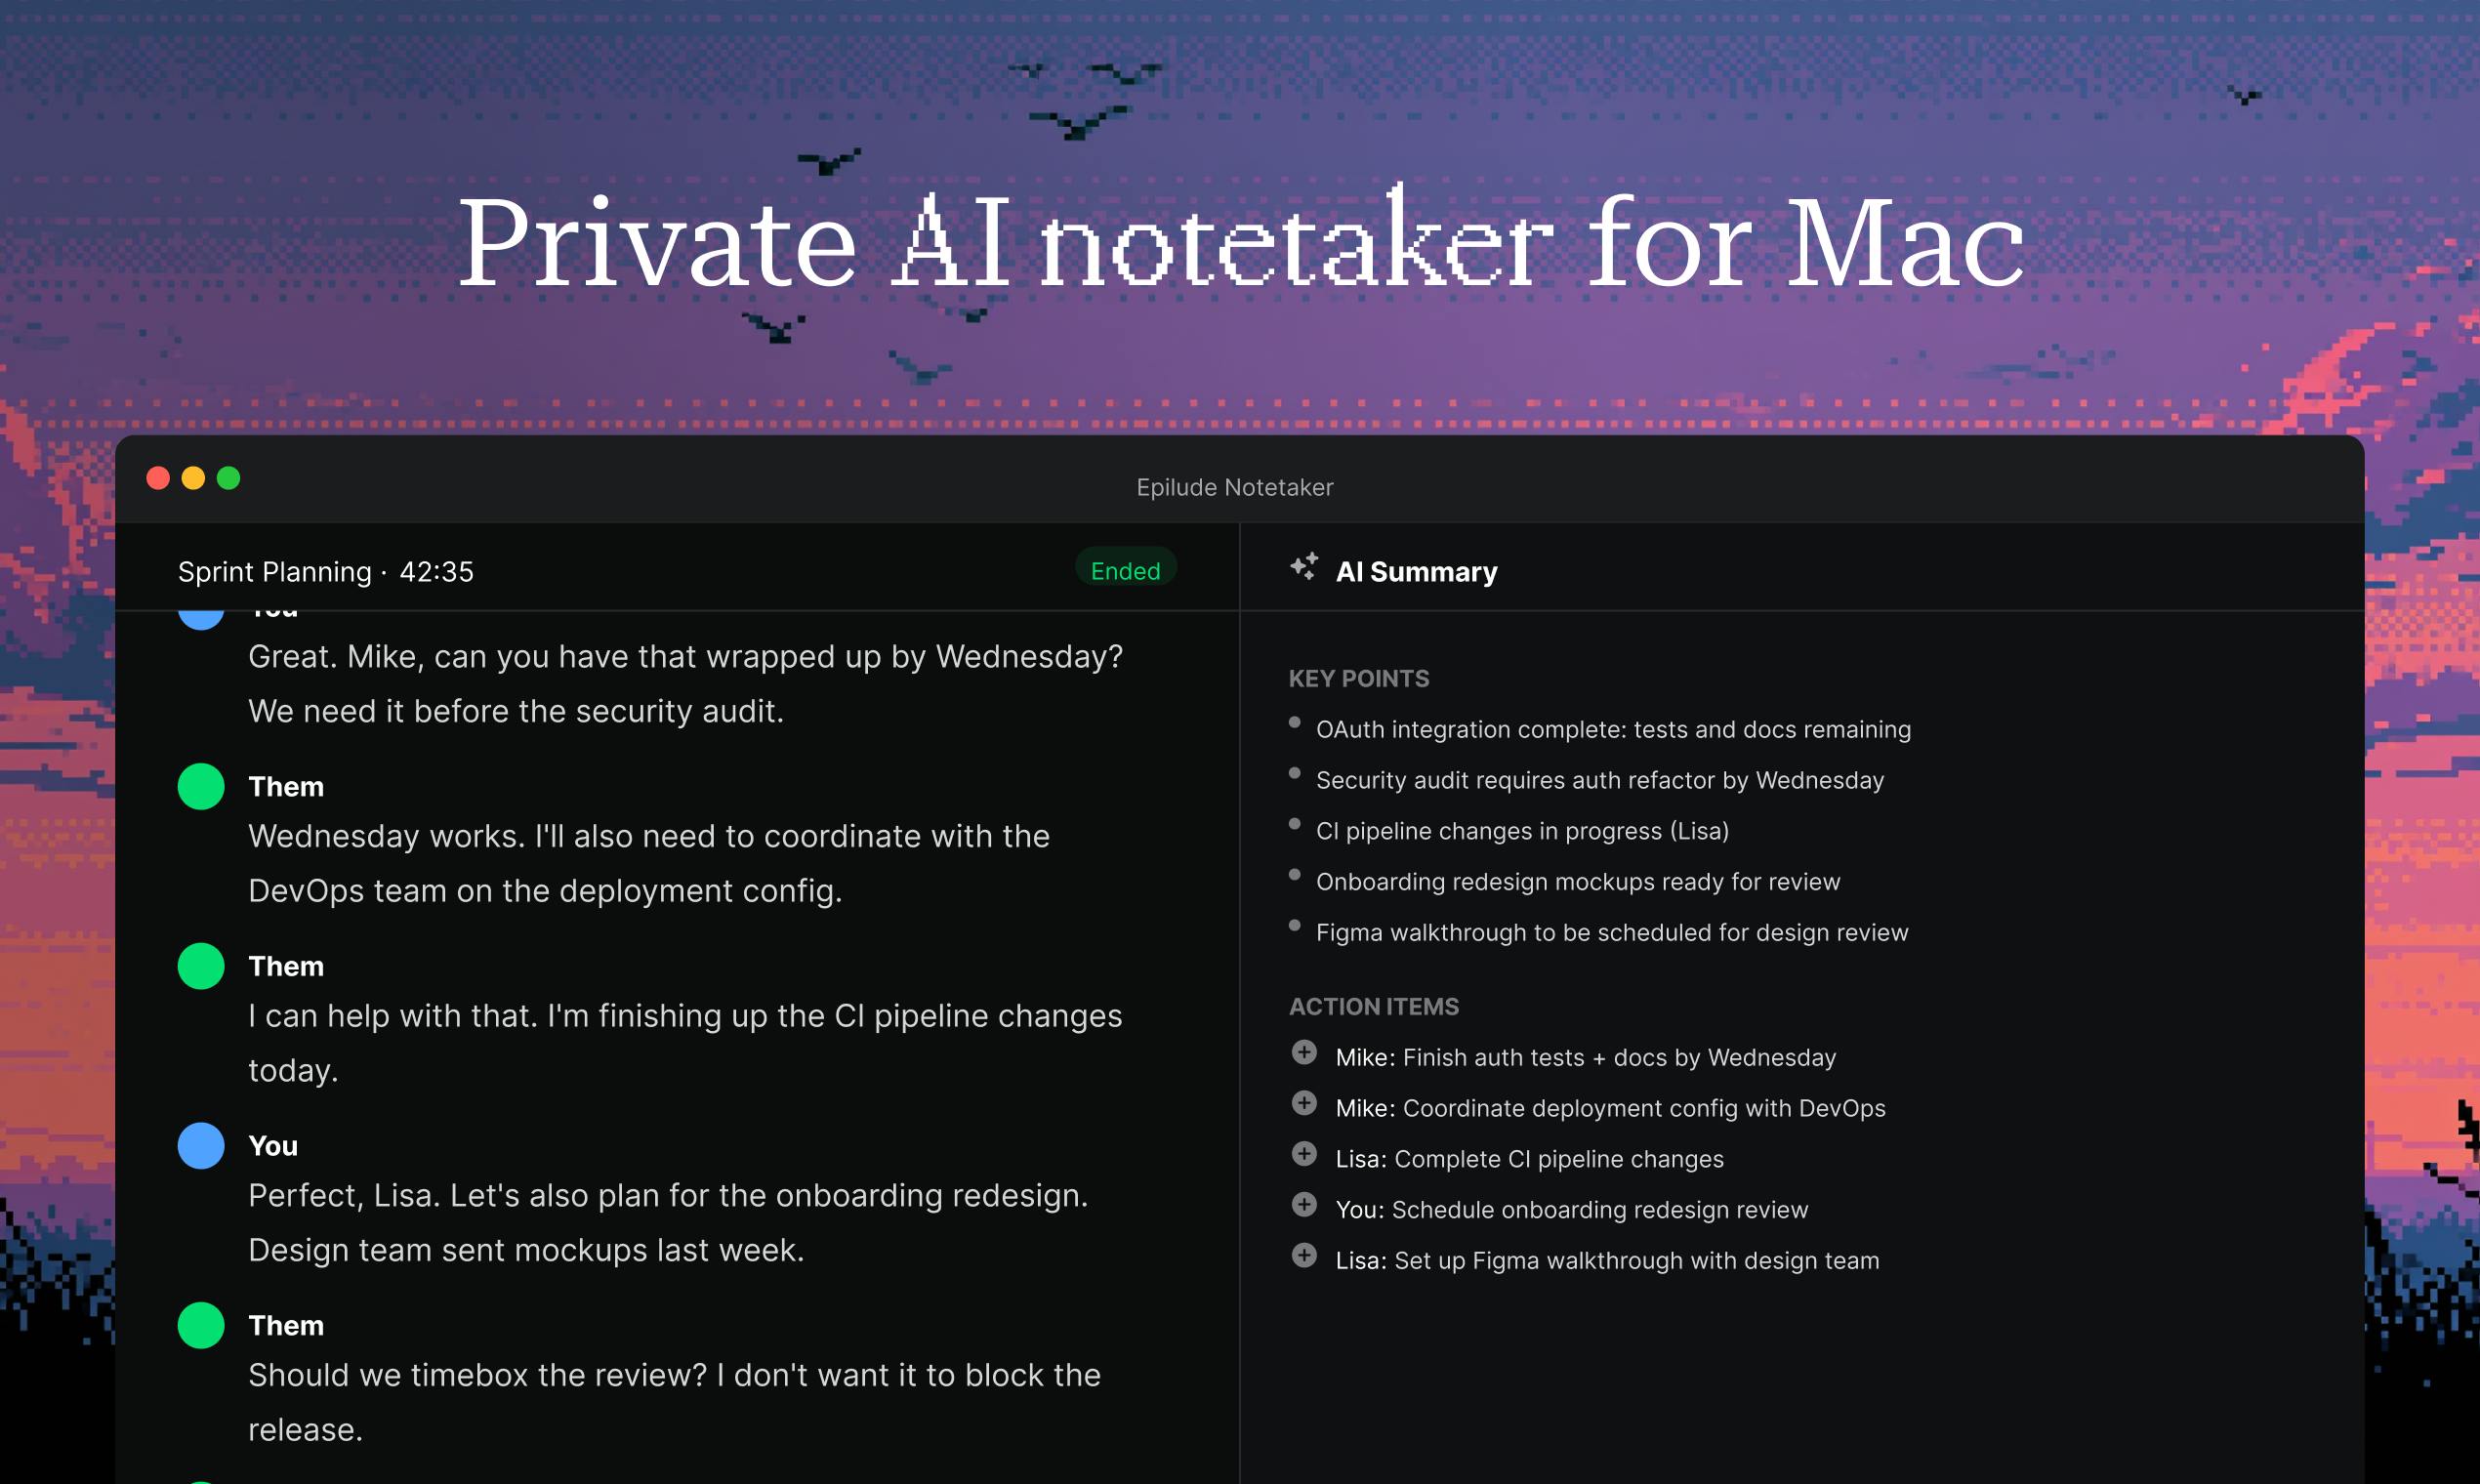
Epilude is a Mac voice-productivity suite with two modules: AI dictation that converts speech into polished, tone-matched text in any app, and Notetaker, which records meetings directly from the Mac — with no bot joining the call — then generates transcripts, editable summaries, and action items saved as user-owned Markdown files. Its distinguishing asset is EP-1, a proprietary local model that performs transcription and summarization entirely on-device, so audio never leaves the customer’s computer. epilude
The target user is a Mac-based professional who talks for a living — consultants, executives, journalists, developers — with a plausible premium segment in privacy-sensitive industries (legal, finance, healthcare, EU-based firms) where cloud notetakers create data-protection friction. The strongest positive signal is execution quality: a two-person team shipping its own on-device model, a second Product Hunt launch within months (97 upvotes, #9 on the daily leaderboard), and transparent, unusually user-friendly pricing ($59 pay-once or ~$144/year Pro). hunted
The most important investment concern is structural, not qualitative: this is a low-ARPU, Mac-only prosumer utility whose founders explicitly reject venture-style growth — the website criticizes “venture capital-backed” voice companies and describes Epilude as “fully bootstrapped and default alive”. A $1B outcome would require roughly 1 million paying Pro subscribers at current pricing, against free alternatives (Apple’s built-in dictation, open-source Whisper apps) and bundled AI notetakers from Zoom, Teams, and Google Meet. epilude
Revenue, users, retention, team size, legal entity, and founder backgrounds are not publicly disclosed. The product is genuinely good and the privacy positioning is a real wedge, but nothing about the current model or stated strategy fits a venture fund’s return requirements. Final decision: Pass — a strong candidate as an indie/bootstrap business, not as a venture investment, with a clearly defined reconsideration path.
Product Overview
Customer problem. Typing is slow relative to speaking, and meeting notes don’t get written. Existing solutions force a trade-off: fast cloud AI that sends your voice to third-party servers, or a visible “AI notetaker” bot in every call, which many clients and colleagues find intrusive. epilude
How it works. For dictation: hold a hotkey, speak, release — cleaned-up, punctuated, tone-matched text lands in any text field. For Notetaker: the app captures the Mac’s microphone and system audio locally during Zoom/Meet/Teams calls, then produces a transcript, an editable summary, and action items with owners and due dates, saved as Markdown in a user-chosen folder. epilude
Core features and platforms. Mac only, requiring Apple Silicon (16GB RAM) for on-device AI cleanup; Cloud Mode works on any Mac. AI Smart Edits, custom vocabulary, voice shortcuts, Tone Match, 25+ languages on-device (30+ in cloud), Notetaker, Markdown export. Teams features (admin controls, shared vocabulary, shared notes) are listed as “coming soon”; Windows, iOS, and Android are stated future plans with no dates. epilude
Pricing (verified from the official pricing page): epilude
- Free trial: 1,000 dictation words and 10 meeting notes, no time limit, no credit card
- Pay Once: $59 one-time — unlimited on-device dictation and meetings, one year of app/model updates
- Pro: $18/month billed monthly or $12/month billed annually ($144/year) — Cloud Mode, longer-meeting cloud summaries, 30+ languages, Intel Mac support
Replaces: Otter/Fireflies/Fathom-style bot notetakers, cloud dictation tools like Voicy, and free Whisper-based utilities — for users whose primary requirement is privacy. reddit
Founder and Team Assessment
Two co-founders are identified only by first names on the official site: Gustav and Mark. The Product Hunt hunter is Gustav Ek. A LinkedIn profile for a Gustav Ek, a senior software engineer in Sweden, exists but the connection to Epilude is not verified — no public profile, interview, or filing independently confirms either founder’s full background, prior companies, or exits. Team size beyond the two founders is unknown; no job listings were found. epilude
What can be assessed is demonstrated execution: shipping a native Mac app, a proprietary on-device model (EP-1), a functioning commercial billing stack, and two Product Hunt launches within roughly six months. That evidences strong technical capability and fast shipping cadence. Commercial capability is partially evidenced by a thoughtful pricing page and active, responsive maker engagement in launch comments. The founders’ anti-VC, sustainability-first positioning suggests committed, long-horizon operators — but also operators whose incentives diverge from venture growth targets. epilude
Founder Assessment: Strong technical execution and credible product instincts, but identity, background, and team depth are only partially verified, and the founders’ stated philosophy is explicitly non-venture.
Market Opportunity
The initial segment is narrow: Mac-using professionals in English- and European-language markets who dictate frequently or take many meetings, and who care enough about audio privacy to pay for it. Willingness to pay is modest — $59 lifetime or ~$144/year — which caps annual revenue per customer well below B2B SaaS norms.
Bottom-up estimate (analyst assumption): assume 100M+ active Macs globally, of which perhaps 3–5 million users are “heavy talkers” with privacy sensitivity. At a blended ~$70/year ARPU (mix of Pro subscribers and amortized one-time purchases), a fully penetrated realistic serviceable market is roughly $200M–$350M in annual revenue. This can support an excellent bootstrapped business, but at the top end it barely overlaps the entry range for venture-scale outcomes.
Expansion levers exist but are unproven: a Teams tier (coming soon), Windows/iOS/Android, and the privacy-compliance angle for regulated industries, which could raise ACV substantially if it becomes an enterprise product. Timing is favorable — on-device model quality is improving rapidly, and GDPR/AI-privacy scrutiny of cloud notetakers is rising — but Apple’s own dictation improvements and bundled AI notes from meeting platforms erode the advantage from the other direction. epilude
Traction and Growth Signals
- Product Hunt (second launch, Notetaker): 97 upvotes, #9 daily placement, active maker dialogue in comments; the main product page has 249 followers. hunted
- Product is live, downloadable, and monetized with published pricing — verified. epilude
- Company claims “default alive” profitability — company-reported, not verified. epilude
- Testimonials on the website (“three weeks in and I dictate almost all of my email”) are unvetted marketing copy. epilude
- Revenue, paying customers, downloads, retention, conversion, traffic, and search interest: not publicly disclosed; no reliable public information was found.
- No App Store listing (direct distribution), no public GitHub, no hiring signals found.
The most important missing metrics: paying customer count, free-trial conversion, and any evidence of organic acquisition beyond launch spikes. Two launches in six months shows marketing persistence, not sustained commercial traction.
Traction Assessment: Credible product and engaged launch community, but commercially unverified.
Competitive Position
- Direct competitors: Voicy and other Mac dictation apps; bot-free notetakers such as Granola, Circleback, and Reflect. usevoicy
- Bundled/platform threats: Apple’s built-in dictation (free, improving each macOS release), and Zoom AI Companion, Teams Intelligent Recap, and Google Meet “take notes for me” — free with the platforms where meetings already happen.
- Free alternatives: FluidVoice, Voicetype, and other local Whisper-based tools discussed actively in Mac communities. reddit
Differentiation is real but shallow: EP-1’s fully local pipeline is currently distinctive in this niche, and the no-bot, Markdown-owned-files workflow has genuine appeal to privacy-sensitive professionals. There are, however, no network effects, low switching costs (notes are portable Markdown by design), and no proprietary data advantage — the company explicitly does not train on user data. The critical question — if Apple or Zoom shipped equivalent on-device private notetaking within six months, why would customers stay? — has only a partial answer: speed, cross-app integration, and neutrality across meeting platforms. That is a feature lead, not a moat. epilude
Defensibility Assessment: Low.
Business Model and Economics
The model is freemium with a deliberately low-friction pay-once tier — a philosophical choice the founders defend publicly as an alternative to forced subscriptions. Economically this is the core issue: $59 one-time purchases (with a year of updates) generate little recurring revenue, while Pro at $144/year carries cloud inference costs for transcription and summaries, with fair-use limits. Local Mode on Pay Once shifts inference costs to the customer’s own hardware — excellent for gross margin, but it also means the revenue-bearing tier is the one with the company-borne costs. Whether usage growth on Pro increases revenue faster than cloud inference costs is not assessable from public data. epilude
Positive notes: no App Store fees (direct distribution), no sales team implied, and a support-light product. The Teams tier (coming soon) is the only visible path to meaningfully higher ACV. epilude
Unicorn Path
Assume a 6–8× ARR multiple for a mature vertical productivity software business (consistent with public SMB-software comparables; a premium AI multiple would require growth the model does not generate). Required revenue: $1B ÷ 7× ≈ $140M ARR.
At current pricing this implies roughly 1 million Pro subscribers ($144/year), or — if the business model changed — perhaps 150,000–250,000 team/enterprise seats at $600–$1,000 ACV. Against a realistic serviceable market estimated at $200M–$350M annually, the current model mathematically cannot reach $140M ARR. Reaching it would require a strategic transformation the founders have publicly positioned themselves against: raising capital, building an enterprise privacy-compliance product, expanding beyond Mac, and abandoning the pay-once ethos. epilude
Unicorn Path: Improbable — achievable only via a business-model transformation into an enterprise team product that contradicts the company’s stated strategy.
Valuation Assessment
No funding history, investors, rounds, or valuations exist in any public source; the company states it is fully bootstrapped. epilude
Valuation Attractiveness: Not Assessable. There is no financing to evaluate. Assessment would require: current revenue and growth, paying-customer count, conversion and retention, gross margin, any SAFE or round terms, and founder ownership. Nothing here can be responsibly priced from Product Hunt performance or product quality.
Key Risks
- Platform bundling — Apple, Zoom, Microsoft, and Google giving away “good enough” AI notes and dictation (most material)
- Low recurring revenue — $59 pay-once tier structurally suppresses ARR
- Mac-only market ceiling — a single-platform prosumer niche
- No verified commercial traction — profitability claim is company-reported only
- Free open-source alternatives — local Whisper tools improving quickly reddit
- Key-person risk — two founders, backgrounds unverified
- Apple Silicon/16GB hardware requirement limits the local-mode addressable base epilude
- Deliberate anti-VC positioning — the company may not want venture capital at any price epilude
Final Assessment
Venture Potential: 45/100
| Category | Score |
|---|---|
| Market Size and Expansion Potential | 10/20 |
| Traction and Growth Evidence | 4/20 |
| Founder and Team | 7/15 |
| Product Strength | 8/10 |
| Distribution Potential | 7/15 |
| Business Model and Economics | 5/10 |
| Defensibility | 4/10 |
| Total | 45/100 |
Strongest element: product quality and shipping velocity, including a proprietary on-device model from a two-person team. Weakest elements: a business model (pay-once, low ARPU, Mac-only) that cannot mathematically produce venture-scale revenue, and a founder philosophy explicitly opposed to venture growth.
Evidence Confidence: 50/100
Verified: product existence and feature set, published pricing, launch performance (97 upvotes, #9), two-launch history, founder first names and hunter identity. Company-reported only: bootstrapped status, “default alive” profitability, testimonials. Unknown: revenue, customers, conversion, retention, team size, legal entity, headquarters, full founder backgrounds. Evidence Confidence is limited despite a polished public presence because no commercial data is externally verifiable.
Final Decision: Pass
Venture Potential is 45/100 (niche/bootstrap profile), the Unicorn Path is Improbable at current pricing and platform scope, Valuation is Not Assessable, and the founders have publicly defined themselves against venture-style growth. This is a well-executed product from a disciplined small team that appears designed to succeed as an indie business — which is precisely why it does not fit a venture mandate. Pass reflects fund-fit, not product quality.
Upgrade Conditions
- A launched Teams/enterprise tier with recurring per-seat revenue and early ARR evidence
- Demonstrated penetration of privacy-regulated verticals (legal, finance, healthcare, EU enterprises)
- Expansion to Windows/iOS with retention of the local-model advantage
- Verified revenue or customer counts showing growth beyond the prosumer niche
Downgrade Conditions
- Apple or a major meeting platform shipping equivalent on-device private notes
- Windows/mobile plans cancelled or indefinitely stalled
- Evidence the product is not profitable or the founders have deprioritized it
- Free local alternatives matching quality and language coverage
Questions for Further Diligence
- What is current MRR and what share of revenue is Pay Once versus Pro?
- How many paying customers, and what is the trial-to-paid conversion rate?
- What is 90-day and 180-day retention for Pro subscribers?
- What are cloud inference costs per Pro user, and do fair-use limits protect margin?
- What is the update-renewal rate for Pay Once customers after year one?
- How large is the team, and are both founders full-time?
- What is the legal entity and jurisdiction?
- What traction exists so far in regulated industries for the privacy angle?
- What is the roadmap and pricing assumption for the Teams tier?
- Would the founders accept external capital at all, and under what conditions?
- How does EP-1 compare on accuracy and speed against Whisper-class open models?
- What is the realistic timeline and cost for Windows and iOS versions?
Sources
- Product Hunt — Epilude (primary launch page)
- Epilude official website (product, EP-1, company positioning)
- Epilude pricing page (verified pricing, trial terms, roadmap)
- Hunted.space launch dashboard (secondary; upvotes and ranking data)
- TechShark — Epilude review (secondary; pricing cross-check)
- r/macapps — dictation discussion (community context on free alternatives)
- Voicy (direct competitor)