
Table of Contents
Jottoo Investment Report
Category: AI meeting notes / productivity SaaS (transcription-to-task workflow)
Company Stage: Pre-seed / just-launched (appears to be a solo, likely bootstrapped project; not verified)
Founder or Founders: Fady Sharobeem (name referenced in Product Hunt launch discussion; background not independently verified) producthunt
Headquarters: Not publicly disclosed
Funding: Not publicly disclosed; no funding announcements or investor lists were found
Business Model: Consumer/prosumer subscription — flat $13.99/month jottoo
Product Hunt Launch Date: September 16, 2026 producthunt
Report Date: September 19, 2026
| Investment Metric | Assessment |
|---|---|
| Venture Potential | 40/100 |
| Unicorn Path | Improbable |
| Valuation Attractiveness | Not Assessable |
| Evidence Confidence | 30/100 |
| Final Decision | Watch |
Executive Summary
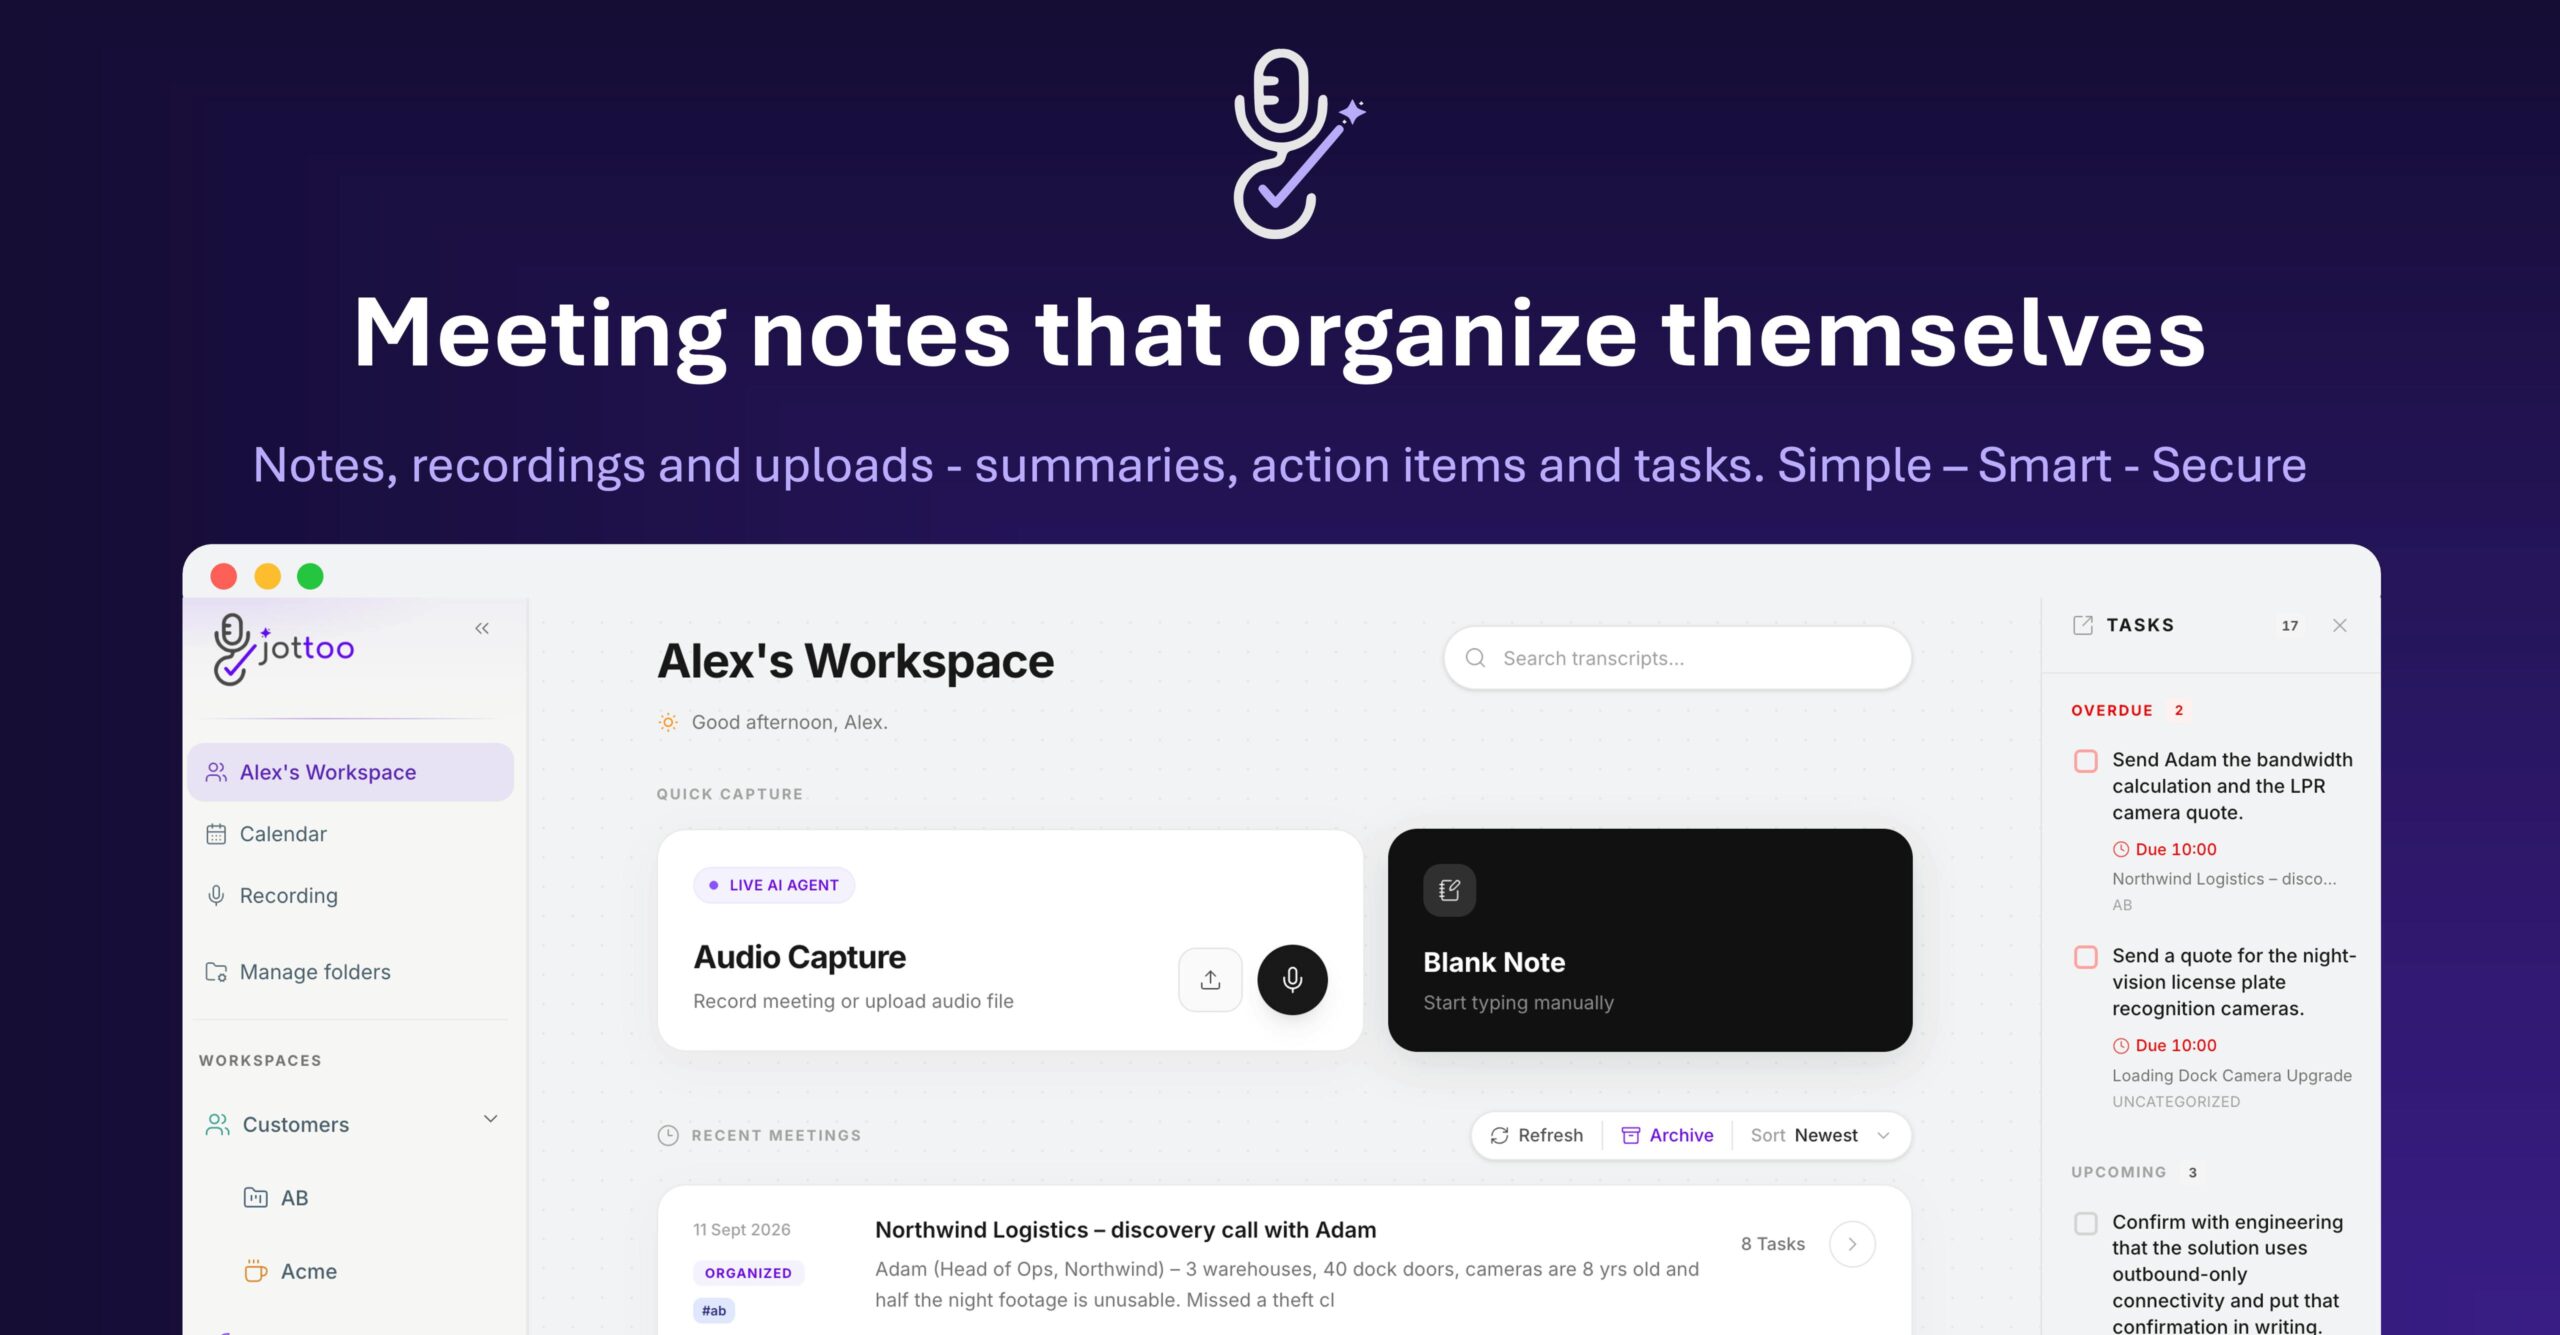
Jottoo is an AI meeting-notes application that records, transcribes, and summarizes meetings — whether recorded, uploaded, or typed — and converts follow-ups into deadline-tracked tasks. Its differentiators are privacy-forward positioning (local-first design, encrypted sync, no advertising model, and no bot joining calls) and the “notes-to-tasks” workflow that goes beyond a raw transcript. The target user appears to be individual professionals and consultants who hold in-person or client meetings and need reliable follow-through, not just documentation. producthunt
The strongest positive investment signal is genuine product differentiation in the “no-bot, no-install, task-oriented” niche, plus founder responsiveness in launch discussions, which suggests active development and direct user engagement. Pricing is straightforward at $13.99/month with a 7-day free trial, processed via Stripe on the web. producthunt
The most important concern is that Jottoo launched publicly three days before this report, with no disclosed revenue, users, funding, team, or retention data — and no integrations yet with the calendar, project-management, or meeting platforms where competitors live. The AI meeting-notes market is intensely commoditized, with free, bundled alternatives from Zoom, Microsoft Teams, Apple, and dozens of funded startups such as Otter, Granola, Notta, and Avoma. producthunt
A unicorn path under the current model would require roughly 745,000 paying subscribers at current pricing — an implausible target for a solo project in a market where incumbents bundle the core feature for free. The final decision is Watch: the product thesis is coherent and the execution is early but active, but there is no commercial evidence yet to justify formal diligence.
Product Overview
Problem: AI notetakers typically either require a bot to join the call or dump a transcript without follow-through. Users leave meetings without a clear record of what they committed to, by when, and to whom. roipad
How it works: Users record a meeting, upload audio, or type a note on the web app (Chrome, Firefox, Safari, Edge). Jottoo produces a searchable transcript, extracts key decisions and highlights, and turns follow-ups into tasks with deadlines, managed in an in-app calendar view. An “Ask Jottoo” feature answers questions about past meetings (currently scoped to a single meeting or note). producthunt
Target users: Individual professionals, consultants, and client-facing workers — especially those with in-person meetings where bot-based notetakers cannot operate. Mobile (iOS and Android) apps are in closed beta. producthunt
Pricing: One flat plan, $13.99/month (tax excluded), 7-day free trial, no credit card required. No free tier beyond the trial is evidenced, despite a “Free Options” tag on Product Hunt. producthunt
Platforms: Web today; mobile in closed beta; no Linux-specific app, no third-party integrations (Linear, Asana, external calendars) as of launch. producthunt
Primary benefit: Walking out of a meeting with an accurate record of commitments and deadlines. Replaced workflow: manual note-taking plus manual transfer of follow-ups into a to-do list or calendar.
Product quality appears solid based on the website, terms, and interactive demo, but no independent reviews, app store ratings, or verified user testimonials were found.
Founder and Team Assessment
The founder is identified only as Fady Sharobeem, referenced in the Product Hunt discussion. A founder quote describing the motivation for building the product (“I got tired of AI note-takers that either require a bot to join your call or hand you a transcript and call it done”) appears on a secondary analytics site, consistent with a solo builder. LinkedIn lists three profiles under this name; the most prominent is a Sydney-based solutions engineering manager currently employed full-time at Verkada since January 2025 — which either means the profiles refer to different people, or that Jottoo is a side project. This cannot be resolved from public information. producthunt
There is no company LinkedIn page, no GitHub organization, no press coverage, and no team information found. All launch replies come from a single voice, suggesting a one-person company, but team size is not verified. Founder background, prior exits, technical and commercial track record, and full-time commitment are all not assessable from public sources.
Founder Assessment: Product-minded solo builder with responsive community engagement, but background, commitment, and commercial capability are unverified.
Market Opportunity
The narrowly defined initial segment is individual client-facing professionals (consultants, freelancers, account managers, recruiters) who hold in-person or mixed meetings, value privacy, and will pay ~$168/year for reliable meeting-to-task follow-through.
A rough bottom-up estimate: if 5–10 million English-speaking professionals globally fit this profile and 1–2% might pay for a specialized tool at ~$168/year, that implies an addressable revenue pool of roughly $85M–$335M per year — a range based entirely on analyst assumptions, not disclosed data. This could support a meaningful bootstrapped or small SaaS business, but capturing even 5% of it would require distribution assets Jottoo does not yet have.
Adjacent expansion opportunities exist — teams, SMBs, regulated industries with recording-compliance needs — but the privacy/local-first positioning cuts against the collaborative, multi-user features that drive team expansion. Timing is challenging: the AI-notes category peaked as a differentiation story in 2023–2025 and is now consolidating into free bundled offerings. jotme
Traction and Growth Signals
- Product Hunt: Launched September 16, 2026; ranked #11 on the daily leaderboard (as a promoted product); 94 followers; launch comments were positive, particularly on the no-bot approach. producthunt
- Launch commentary: Commenters requested Linux support and integrations with Linear, Asana, and external calendars — none exist yet. producthunt
- Product activity: Terms and privacy pages updated August 1, 2026; mobile apps in closed beta — indicating recent, ongoing development. jottoo
- Directory listings: Listed on a GitHub “awesome-ai-startups” compilation and Chinese AI directories within days of launch — passive, not commercial traction. github
Missing metrics (all not publicly disclosed): revenue, ARR/MRR, paying customers, registered or active users, retention, conversion from trial to paid, website traffic, app store performance, hiring, partnerships, and funding. Product Hunt attention is three days old and cannot distinguish sustained demand from launch-day interest.
Traction Assessment: Early and encouraging community reception, but commercially unverified with no sustained post-launch data.
Competitive Position
- Direct competitors: Otter, Granola, Notta, Avoma, JotMe, HyNote AI, AudioPen, Notello, and dozens of app-store AI notetakers. jotme
- Bundled/platform threats: Zoom AI Companion, Microsoft Teams Copilot, Google Meet’s Gemini notes, and Apple’s on-device intelligence effectively give away meeting summarization at zero incremental cost to hundreds of millions of users.
- Free/manual alternatives: native voice memos plus Apple Notes/Reminders, or a plain LLM prompted with a transcript.
Jottoo’s differentiation — no bot, local-first storage, encrypted sync, and a task-tracking loop rather than a transcript dump — is real but narrow. There are no switching costs, no proprietary data assets, no network effects, and no workflow integrations yet. If Zoom, Apple, or Otter shipped “notes that become tasks” tomorrow — Otter and others already extract action items — Jottoo’s answer would rest almost entirely on privacy and price, which historically does not retain prosumer users at scale. jottoo
Defensibility Assessment: Low.
Business Model and Economics
Revenue comes from a single $13.99/month subscription billed via Stripe on web (avoiding the ~15–30% app store fee for web-billed subscriptions, though mobile-billed subscriptions would incur it). Gross margin is not disclosed and must be estimated: each user consumes transcription (speech-to-text) plus LLM summarization and Q&A inference. At ~$14/month flat with unlimited recording and “Ask Jottoo” usage, heavy users could push inference costs uncomfortably close to subscription price; light users subsidize them. Whether usage growth increases revenue faster than costs is not assessable — usage-based pricing tiers, cost caps, and per-user inference economics are all unknown. Free-to-paid conversion, churn, and retention are likewise unknown. Customer acquisition currently relies on launch platforms (Product Hunt, directories) with no evident SEO, content, or referral engine. workspace.jottoo
Unicorn Path
Assume a 8x revenue multiple, typical for a high-growth SaaS/AI subscription business. Required revenue = $1 billion ÷ 8 = $125M ARR. At $168/year per subscriber, that requires roughly 745,000 paying subscribers. Even at an optimistic 10x multiple, the requirement is ~600,000 subscribers.
For context, reaching that scale would demand consumer-subscription distribution comparable to top-tier productivity apps, in a category where the largest platforms bundle the core function free. Achieving it would require strategic changes: team/enterprise plans at 5–10x the ACV, deep calendar/PM-tool integrations to become workflow-embedded, proprietary meeting-outcome data, a repeatable acquisition channel beyond launch sites, external capital, and a team — all while incumbents compress the paid market.
Unicorn Path: Improbable.
Valuation Assessment
No funding history, investors, round size, SAFE caps, or valuation information exists publicly, and no comparable private financings for this specific company were identified. Revenue is not disclosed, so revenue-multiple comparables cannot be applied.
Valuation Attractiveness: Not Assessable. To assess it, an investor would need: current ARR, revenue growth, gross margin, retention, burn rate, runway, round size or SAFE cap, post-money valuation, investor ownership, and liquidation preferences.
Key Risks
- Commoditization by bundled incumbents — Zoom, Teams, and Apple give away meeting summarization, shrinking the paid market.
- No commercial validation — zero public revenue, user, or retention evidence three days post-launch.
- Solo-founder and possible part-time commitment — a LinkedIn profile matching the founder’s name shows current full-time employment elsewhere; the relationship is unverified. linkedin
- Weak distribution — no integrations, no SEO assets, dependence on launch-platform spikes.
- Flat pricing vs. usage-based AI costs — unlimited transcription plus Q&A at $13.99/month creates margin risk from heavy users.
- Low switching costs — notes and tasks are easily exportable; competitors can match features quickly.
- No team features — limits ACV expansion and enterprise motion.
- Category saturation — dozens of funded competitors and app-store clones compete on price. jotme
- Recording-law compliance burden — terms place all wiretapping/consent-law responsibility on users, which is standard but leaves exposure in regulated segments. workspace.jottoo
Final Assessment
Venture Potential: 40/100
| Category | Score |
|---|---|
| Market Size and Expansion Potential | 11/20 |
| Traction and Growth Evidence | 4/20 |
| Founder and Team | 5/15 |
| Product Strength | 6/10 |
| Distribution Potential | 5/15 |
| Business Model and Economics | 5/10 |
| Defensibility | 4/10 |
| Total | 40/100 |
Strongest element: a genuinely differentiated, well-scoped product thesis (no-bot, privacy-first, notes-to-tasks) in a real pain area. Weakest elements: no commercial validation, a likely solo founder whose background cannot be verified, near-zero defensibility, and no distribution assets.
Evidence Confidence: 30/100
Verified: product existence, features, pricing, terms of service, privacy policy, PH launch performance. Company-reported: founder motivation quote (via secondary site). Unknown: revenue, users, retention, funding, team, legal entity, headquarters, and founder background. This is very limited reliable information, dragged down by the inability to confirm even the founder’s professional identity.
Final Decision: Watch
Jottoo is interesting as a product — coherent, differentiated, actively developed — but as a venture investment it currently fails every test that matters: no traction evidence, no team visibility, no funding or valuation data, low defensibility, and an improbable path to venture-scale revenue at current pricing. This is exactly the profile of a promising bootstrapped business rather than a venture candidate at this stage. Watch is appropriate because the product merits post-launch observation, but nothing yet justifies formal diligence.
Upgrade Conditions
- Verified traction: e.g., ≥$10K MRR or several hundred paying customers, disclosed or verifiable
- Sustained product cadence: shipped mobile apps plus calendar/PM integrations within two quarters
- Demonstrated retention: trial-to-paid conversion above ~10% and six-month retention above 50%
- A verifiable founder profile showing either full-time commitment or a credible team
- Repeatable acquisition beyond launch platforms (SEO, referral, or partnership)
Downgrade Conditions
- Product activity stalls or the founder stops responding/working on it
- Otter, Zoom, or Apple ship equivalent task-extraction features (further commoditizing the paid tier)
- Signs of margin stress, such as usage caps appearing or price increases
- No measurable commercial traction within 6–9 months post-launch
Questions for Further Diligence
- What is current MRR, and how many paying subscribers do you have today?
- What is trial-to-paid conversion, and 30/90/180-day retention by cohort?
- What share of subscribers are heavy users, and what is your average inference and transcription cost per subscriber per month?
- Is Jottoo your full-time commitment, and what is your employment status?
- What is the legal entity, jurisdiction, and cap table?
- Have you raised or are you raising capital, and on what terms (SAFE cap, post-money)?
- Which integrations (calendar, Linear, Asana, Slack) are prioritized and when?
- What was week-over-week signup and usage trend since the September 16 launch?
- What is your churn rate and primary cancellation reason?
- How do you plan to acquire customers beyond Product Hunt and directories?
- Does local-first/encrypted sync limit future team features, and how would you serve teams?
- What recording-consent compliance obligations do you anticipate for regulated customers?
Sources
- Product Hunt — Jottoo producthunt
- Jottoo official website jottoo
- Jottoo Terms of Service workspace.jottoo
- Jottoo Privacy Policy workspace.jottoo
- Product Hunt leaderboard, September 16, 2026 producthunt
- Product Hunt — Jottoo alternatives producthunt
- ROIPad — Jottoo origin analysis (secondary source, founder quote) roipad
- LinkedIn — Fady Sharobeem (identity match unverified) linkedin
- JotMe — Best AI notetakers 2026 (competitor landscape, secondary source) jotme
- GitHub — awesome-ai-startups directory listing (secondary source) github